Skip to content

Jumbo Non-QM Loans in the Texas Hill Country

Horseshoe Bay, Fredericksburg, Spicewood and Kingsland attract buyers purchasing waterfront homes on Lake LBJ and Lake Travis, ranch acreage and golf community properties throughout the Texas Hill Country. LendFriend offers jumbo Non-QM financing, including asset depletion loans for borrowers with substantial investment portfolios and bank statement loans for self-employed buyers, with more flexible qualification options than many traditional banks offer.

Why Homebuyers Trust LendFriend With Their Jumbo Loans in the Texas Hill Country

A lake house or ranch property in the Hill Country often costs more than a conventional jumbo lender will finance on standard terms. LendFriend is a mortgage broker with access to jumbo and jumbo Non-QM programs from more than 40 wholesale lenders. We work with buyers of second homes, primary residences, acreage and investment properties.

We regularly help buyers finance homes in Horseshoe Bay, Fredericksburg, Spicewood, Kingsland, Marble Falls and Kerrville. Acreage, waterfront values and income that comes from a business or a portfolio can each make lender guidelines harder to meet in these markets.

Jumbo Loans Built Around the Borrower

W-2 earners with long job histories and solid reserves tend to qualify without much difficulty. Hill Country buyers are more often retirees, ranch owners and business owners whose wealth sits in accounts and companies rather than on a pay stub.

LendFriend offers jumbo loans for these borrowers, including:

  • Bank statement jumbo loans for eligible self-employed borrowers whose income is documented through 12 or 24 months of business or personal deposits rather than tax returns
  • Asset depletion jumbo loans for borrowers who qualify on eligible brokerage, retirement and savings balances
  • No-ratio jumbo loans for eligible borrowers buying or refinancing a primary residence, with approval resting mainly on credit, assets and the property rather than a traditional income calculation

Financing for Lake Homes, Ranch Land and Weekend Properties

Many Hill Country purchases are second homes used on weekends and later in retirement. Buyers choose waterfront homes on Lake LBJ in Horseshoe Bay and Kingsland, Lake Travis properties in Spicewood, and homes on acreage around Fredericksburg, Blanco and Johnson City.

We help borrowers finance second homes, ranch properties and golf residences while accounting for occupancy, acreage, reserves and the way income or assets are held. Lenders differ on how much land they will accept, and we confirm that point early.

A Faster, More Responsive Jumbo Process

Well-priced waterfront listings in Horseshoe Bay and Spicewood rarely stay on the market long. We review income, assets and credit at the start, then stay in close contact with the lender, appraiser and title company until funding. Our wholesale relationships help qualified files move through underwriting without delay, and prepared borrowers may be able to close a jumbo loan in as little as 14 days.

Trusted by Homebuyers

LendFriend has helped thousands of homebuyers purchase and refinance homes, earning more than 1,000 reviews along the way. Borrowers consistently praise our responsiveness, transparency, mortgage expertise and ability to solve complicated financing challenges.

Loan Programs To Suit Every Hill Country Borrower's Needs!

LendFriend works with more than 40 wholesale lenders to arrange jumbo loan options for buyers who need wider guidelines than one bank provides. The programs below cover bank statement loans, asset depletion loans, and crypto mortgages for qualified Hill Country borrowers.

Asset Depletion Loans in the Texas Hill Country

Asset Depletion Loans in the Texas Hill Country

An asset depletion mortgage allows eligible brokerage accounts, retirement funds and savings to be converted into qualifying income for a lake home or ranch purchase. It can be a strong fit for high-net-worth buyers and retirees in Horseshoe Bay, Fredericksburg and Spicewood whose assets are substantial but whose traditional income may be limited.

Learn More →

Self Employed Mortgages in the Texas Hill Country

Self Employed Mortgages in the Texas Hill Country

Ranch owners, winery operators and other business owners in the Hill Country often report less taxable income than their cash flow would suggest. Our self-employed mortgage options can use bank statements to qualify without relying on tax-return income, giving business owners across Llano, Gillespie, Burnet and Blanco counties more ways to finance a home.

Learn More →

Crypto Mortgages in the Texas Hill Country

Crypto Mortgages in the Texas Hill Country

A crypto mortgage can allow qualified buyers to use Bitcoin, Ethereum and other eligible digital assets to help qualify for a lake home or ranch property without liquidating their holdings. Buyers in Horseshoe Bay, Spicewood and Marble Falls may be able to finance up to $5 million with a jumbo crypto mortgage.

Learn More →

RSU Mortgages For Tech Employees Buying in the Hill Country

RSU Mortgages For Tech Employees Buying in the Hill Country

The Hill Country is a second-home and retirement market with few large stock-paying employers of its own, so most RSU borrowers here work in Austin for companies such as Dell Technologies, Tesla, Apple and Oracle. Our RSU mortgage program can use vested RSU income alongside salary, helping those employees qualify for higher loan amounts without selling shares.

Learn More →

DSCR Loans in the Texas Hill Country

DSCR Loans in the Texas Hill Country

A DSCR loan can allow investors to finance a rental property on the rent it produces rather than on personal tax returns. It can be a strong fit for investment homes on the Highland Lakes and in Fredericksburg, where the lender compares the property's rent to the proposed mortgage payment.

Learn More →

Jumbo No-Ratio Loans in the Texas Hill Country

Jumbo No-Ratio Loans in the Texas Hill Country

With a no-ratio loan, qualifying borrowers can finance a primary residence in the Hill Country without a traditional debt-to-income calculation. These loans can be particularly useful for high-net-worth buyers, investors and business owners in Horseshoe Bay or Kerrville with substantial credit, assets and reserves who may not fit conventional income guidelines.

Learn More →

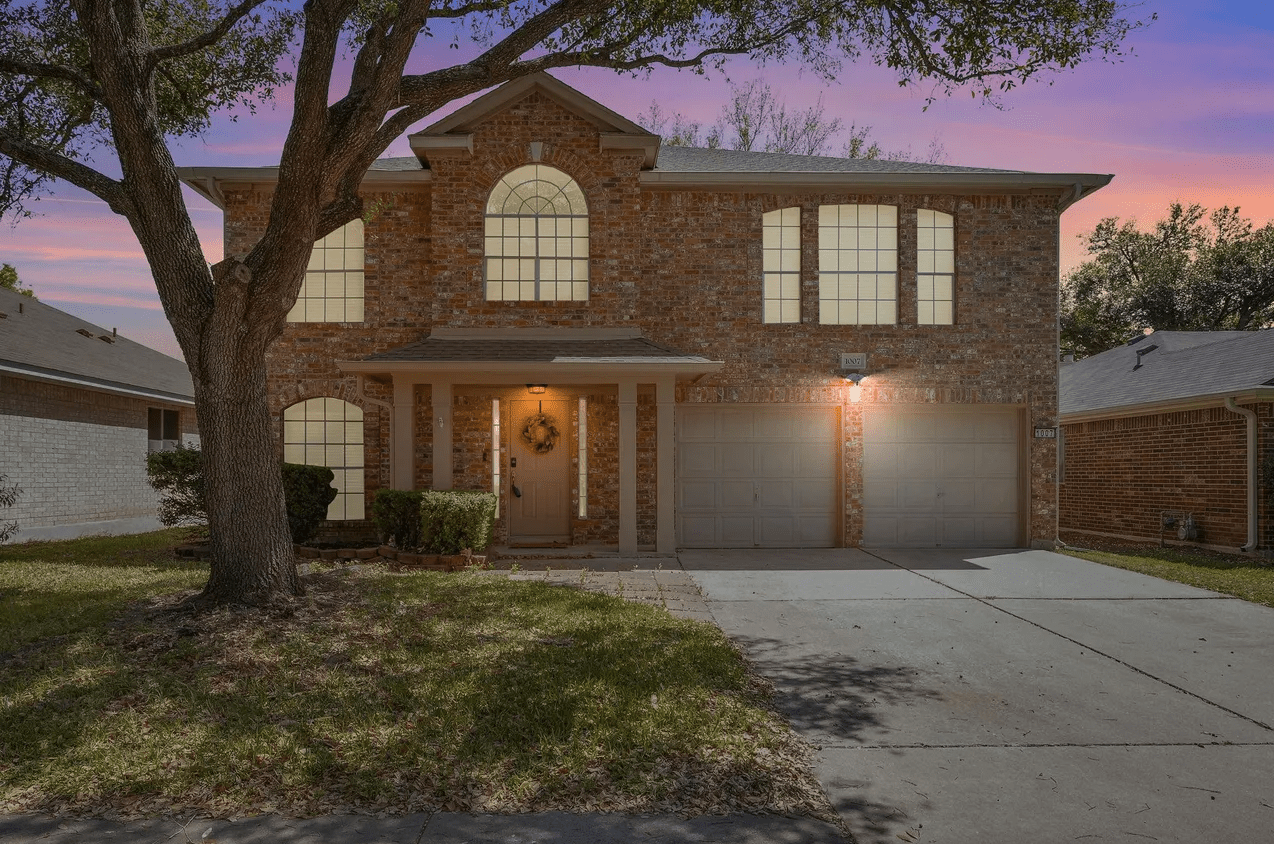
Luxury home near Horseshoe Bay, Texas

Straightforward Qualification That Works for Buyers in Horseshoe Bay, Fredericksburg and Spicewood

Buyers ask us early what it takes to qualify for a jumbo loan in Horseshoe Bay, Fredericksburg, Spicewood or Marble Falls. We review credit, income, assets, reserves and the property before you write an offer, so the programs that fit are known in advance.

Clear qualification guidelines for jumbo loans

We set out credit, debt-to-income, reserve and documentation requirements at the beginning. Second homes and properties on acreage may carry extra requirements, and we explain those before the appraisal is ordered.

More options for self-employed and retired buyers

Business owners who are eligible may use the jumbo bank statement loans LendFriend offers, where deposits replace tax returns. We also arrange jumbo asset depletion loans for retirees and high-net-worth buyers who qualify on eligible investment and retirement assets.

Get Started On Your Texas Hill Country Jumbo Loan

The property may be a Lake LBJ waterfront home in Horseshoe Bay, a residence on acreage outside Fredericksburg or a Lake Travis home in Spicewood. LendFriend can help you find a home loan in Texas that fits the way you earn and hold your wealth.

Schedule a call or apply online to go over your options, current jumbo mortgage rates in the Hill Country and the documents a lender will request. Qualified borrowers can also have the file prepared for a faster closing once a contract is signed.

Screenshot 2025-05-09 at 11.19.56 AM

Jumbo Non-QM Loan Examples for Texas Hill Country Buyers

Retirees, business owners and second-home buyers in the Highland Lakes often need a seven-figure loan that tax returns alone do not support. The four scenarios below are illustrative and describe no actual borrower. Lenders may structure jumbo loans for Texas homes with asset depletion loans, bank statement loans and jumbo no-ratio loans, and the scenarios show how. A jumbo no-ratio loan finances a primary residence only, so it does not apply to a weekend lake house.

$3.2M Asset Depletion Loan in Horseshoe Bay

A Houston couple in their sixties, both retired, are buying a $4.5M waterfront home on Lake LBJ in Horseshoe Bay and hold $11M in brokerage and IRA accounts. A jumbo asset depletion loan can convert part of those balances into qualifying income for a $3.2M mortgage, about 71% of the price. They put $1.3M down and sell nothing to qualify.

$3.3M Cash-Out Asset Depletion Loan in Spicewood

A Spicewood owner holds a Lake Travis home worth about $5.5M with $1.4M left on the mortgage. A jumbo asset depletion loan can qualify a $3.3M cash-out refinance on a $13M portfolio, with no salary or pension documented. The new loan equals 60% of value and returns roughly $1.9M to the owner before closing costs.

$1.9M Bank Statement Loan in Fredericksburg

The owner of a Fredericksburg winery is buying a $2.6M home on acreage, and years of equipment write-offs leave little net income on her returns. A jumbo bank statement loan can qualify a $1.9M mortgage on 24 months of business deposits, with no tax returns in the file. She puts $700,000 down, about 27% of the price.

$1.8M No-Ratio Loan in Kerrville

A Kerrville physician nearing retirement is buying a $3.2M home at Comanche Trace as her primary residence and shows little income after selling her practice. A jumbo no-ratio loan, offered for a primary residence only, can provide a $1.8M mortgage with no debt-to-income ratio calculated. She brings $1.4M to closing, about 44% of the price, and qualifies on credit, reserves and equity.

Jumbo Mortgage Options Beyond the Texas Hill Country

Hill Country owners rarely stop at one property. The lake house is often a second home, the primary residence sits in a Texas metro, and some families add a ski or beach home out of state. We arrange jumbo loans in many of the markets where these owners also buy.

Within Texas, we finance higher-priced homes from the Highland Lakes and Fredericksburg to the major metros and the Gulf Coast. Statewide, our jumbo loans in Texas cover primary residences, second homes and investment properties. Many lake-home buyers keep a primary residence in Austin, including Westlake and Lakeway, about an hour east of Horseshoe Bay.

Others drive in from farther away. We arrange jumbo mortgages in Houston neighborhoods such as River Oaks and Memorial and in Dallas communities such as Highland Park and Preston Hollow.

Texas buyers also purchase out of state. Ski homes lead many of them to Colorado resort towns such as Vail and Breckenridge, and beach homes lead others to Florida markets along 30A and the Gulf Coast.

If the next home is on Lake LBJ, in Austin or Dallas, or in another state entirely, we can review jumbo mortgage options with you before the offer goes in.

BORROWER TESTIMONIALS

See Why Jumbo Borrowers Choose LendFriend Mortgage

See how homebuyers across the country have worked with LendFriend Mortgage to navigate larger loan amounts, complex income, and jumbo mortgage financing.

FAQs – Getting a Jumbo Loan In the Texas Hill Country

What loan amount qualifies as a jumbo loan in Llano County and the Texas Hill Country?

In Llano County, the 2026 conforming loan limit for a one-unit property is $832,750. Any mortgage larger than this figure is treated as a jumbo loan.

The 2026 limits below apply in Llano, Gillespie, Burnet, Blanco, and Kerr counties:

  • Single-unit property: $832,750

  • Two-unit property: $1,066,250

  • Three-unit property: $1,288,800

  • Four-unit property: $1,601,750

Waterfront and ranch properties in Horseshoe Bay, Fredericksburg, Spicewood, and Kingsland regularly exceed these thresholds, so a jumbo mortgage is the usual financing for higher-priced Hill Country homes.

How much can I borrow with a jumbo loan in the Texas Hill Country?

Qualified borrowers can obtain jumbo loans in Texas of several million dollars. The approved amount depends on credit score, loan-to-value ratio, reserves, and whether the home is a primary residence or a second home. Higher credit scores and larger reserves usually bring a lower jumbo rate on a Hill Country purchase.

Do jumbo loans require perfect credit?

No. Borrowers with scores of 750 or above generally earn the strongest jumbo pricing. A borrower with a lower score may still qualify when the file includes a larger down payment, substantial liquid assets, or other compensating strengths.

Can I get a jumbo loan in the Hill Country if I am self-employed or retired?

Yes. Jumbo Non-QM programs for Hill Country buyers include bank statement loans and asset depletion loans. Business owners and retirees buying in Horseshoe Bay or Fredericksburg may qualify without W-2s or traditional tax returns. Lenders offering jumbo bank statement loans in Texas calculate income from 12 or 24 months of deposits, and loan amounts reach $7M.

What property types are eligible for jumbo financing in the Hill Country?

Jumbo lenders accept single-family homes, warrantable and non-warrantable condos, townhomes, and 2–4 unit properties. We arrange jumbo financing for a Lake LBJ waterfront home, a golf residence in Horseshoe Bay, a home on acreage near Fredericksburg, or a Lake Travis property in Spicewood. Lenders differ on how much acreage they will finance, so we confirm the property with the lender before the appraisal is ordered. The lender also needs to know whether the purchase is a second home or an investment property, because occupancy affects pricing and down payment.


How do jumbo loan interest rates compare to conventional rates in Texas?

Jumbo rates in the Hill Country are frequently in line with conventional rates and at times below them. Pricing varies by lender, so Texas jumbo mortgage rates should be compared across several lenders for the same file.

Is an adjustable-rate mortgage a good option for a jumbo loan in the Hill Country?

It can be, and the answer depends on how long you expect to hold the loan. With a 5/1 or 7/1 jumbo ARM, the rate is fixed for five or seven years and often begins below a 30-year fixed rate. The lower early payment is one reason ARMs have returned among jumbo borrowers. Buyers who expect to pay off a second-home mortgage early are common candidates. An owner with a shorter horizon should still weigh whether an ARM makes sense when a sale is planned.

How much equity can I access with a jumbo cash-out refinance in the Texas Hill Country?

Texas law limits a cash-out refinance on a homestead to 80% of the home's value, and lenders may set lower limits on very large loans. Owners in Horseshoe Bay, Marble Falls, and Kerrville can draw on equity through a jumbo cash-out refinance. The new loan pays off the existing mortgage and delivers the remaining proceeds in cash. The rules are specific to this state, and jumbo cash-out refinances in Texas follow the home equity provisions of the Texas Constitution. Hill Country homeowners with VA entitlement may also consider a VA cash-out refinance or a VA jumbo cash-out refinance, and neither carries monthly mortgage insurance.

Are VA jumbo loans available in the Texas Hill Country?

Eligible veterans and service members, including military retirees settling in Kerrville and the Highland Lakes, may be able to use a VA loan above the conventional limit. Qualified borrowers may buy a higher-priced Hill Country residence with $0 down and no monthly PMI. With full entitlement, VA jumbo loans are not capped at the county loan limit.

Can I refinance a jumbo loan in the Hill Country?

Yes. A jumbo refinance can lower the rate, replace an ARM with a fixed loan, or draw equity from a high-value property. Owners of lake homes in Llano and Burnet counties may also refinance to restructure debt or change the loan term.

What can I do if a bank denied my jumbo loan in the Texas Hill Country?

One bank's denial usually reflects its own overlays and says little about whether the borrower can qualify elsewhere. Wholesale jumbo lenders differ in how they treat bonus income, RSUs, ranch and business income, and large asset balances. As a broker, we can move the file to a lender whose guidelines match it. Buyers under contract still have several paths when a jumbo loan is denied in Texas.

How much do I need to put down on a jumbo loan in the Hill Country?

Jumbo lenders generally require 10% to 20% down on a primary residence in the Hill Country. Second homes and investment properties usually call for more, and many Highland Lakes purchases fall in those categories. The smallest down payments go to borrowers with the strongest credit and reserves, including those using 10% down jumbo loans in Texas. Requirements differ by program, and jumbo and Non-QM mortgage down payments depend on credit, occupancy, and loan size.

Learn More About Jumbo Non-QM Loans

And our Learning Center gives you access to everything you need to know about jumbo loans, from down payment options and rate structure to underwriting, reserves, and refinancing. Read some of our favorite jumbo loan articles below.

The LendFriend Advantage for Jumbo Borrowers in Texas

LendFriend Mortgage treats jumbo lending as a primary discipline, including loans on lake homes and ranch property. Each borrower is matched with a jumbo lender that fits the property, the financial profile, and the objective. We charge no hidden fees and run the process to close quickly. Hill Country buyers can choose a 30-year fixed loan, a 7/1 ARM, or a flexible Non-QM option.

Around the Clock

Our team is available seven days a week to answer questions, review pricing and keep your loan moving. Whether you are buying in Horseshoe Bay, Fredericksburg, Spicewood or elsewhere in the Hill Country, you can reach someone who knows your file and can give you a clear answer.

Loan Options

Access fixed-rate jumbo loans, ARMs, bank statement loans, asset depletion loans and other specialized mortgage programs through more than 40 wholesale lenders. This gives us more flexibility to match the financing to your income, assets and property.

Get Pre-Approved Quickly

A strong pre-approval can make a meaningful difference when competing for a higher-priced home. We review your financial profile early, identify the right loan program and issue pre-approvals quickly so you can make an offer with confidence.

Personalized Mortgage Guidance

You work directly with an experienced mortgage professional who helps you understand your options, prepares the file for underwriting and stays involved through closing. Complex income, large asset portfolios and unusual property scenarios get the attention they require.

Close in as little as 14 days

Our lending relationships and experience with larger loan amounts help us move qualified jumbo borrowers through underwriting efficiently. In competitive markets like Horseshoe Bay, Fredericksburg, and Marble Falls, many loans can close in as little as 14 days when timing matters.

Contact us today to get a custom rate quote for your Hill Country home financing in less than 2 minutes.