“Highly recommend Eric and Team!! Very smooth and straightforward the whole way through — especially with our complicated RSU comp. The team had zero issues navigating this.
Their communication was excellent, they laid out a clear timeline upfront and actually stuck to it, and everything just flowed without any headaches.
This has been the least stressful mortgage experience we have had. Thank you!”
RSU Mortgages For Employees With Stock Compensation
Buying a home with RSUs, stock grants, or pre-IPO equity compensation? LendFriend Mortgage helps tech employees, executives, founders, and high-income professionals use eligible RSU income and equity-based compensation to qualify for competitive mortgage options in Texas, Colorado, Illinois, California, and across the U.S.
How Can Restricted Stock Units (RSUs) Help You Qualify for a Mortgage?
At LendFriend Mortgage, we help tech employees, executives, founders, and professionals use RSU income, stock grants, and equity compensation to qualify for a mortgage with fewer roadblocks. Whether you work for a public company in Austin, Houston or any other major tech and business market, our team knows how to document RSU income clearly and match your profile with lenders that understand equity-based compensation.
Here’s how RSUs can strengthen your mortgage approval:
Higher qualifying income: When RSU income is properly documented through pay stubs, W-2s, vesting schedules, grant agreements, and tax records, it may help increase the income used for mortgage qualification. That can improve buying power, especially for borrowers purchasing in higher-cost Texas markets like Austin and Houston.
Flexible down payment source: Vested RSUs may be used as a source of funds for your down payment, closing costs, or reserves. Whether you have already sold shares or plan to liquidate vested stock before closing, we help make sure the paper trail is clean and lender-ready.
Improved debt-to-income ratio: RSU income can play an important role in your overall income profile. We help present your compensation clearly so eligible equity income is reviewed correctly when lenders calculate your debt-to-income ratio.
More loan options: Some banks take a narrow view of RSU income. As a mortgage broker, LendFriend Mortgage can compare dozens of lenders that are more experienced with complex compensation, including RSUs, bonuses, commission income, and pre-IPO equity scenarios.
Most lenders do not fully understand RSUs. We do. For tech employees from Austin to the Bay Area or employees at public companies across the US, we help turn stock-based compensation into a clear, confident path to mortgage approval.
Stronger Negotiating Position when Buying a Home
The equity in your current home is unlocked and used as a downpayment on your new home; meaning no sales contingency required! Sellers HATE sales contingencies. Without a sales contingency, your offer is stronger, increasing your chances of buying your next home with ease.
Get the Highest and Best Sale Price
Without feeling pressured to sell quickly, you can wait for the best offer on your current home. List your home at the best time, market it effectively, and attract more competitive offers. With no rush, you can negotiate better terms and get the highest selling price.
Reduced Stress
Don't worry about finding temporary housing or organizing multiple moves. Avoid the chaos of having to coordinate the sale of your current home and the purchase of a new one. Transition seamlessly from one home to another and reduce stress or anxiety, making the moving process more manageable and organized.
Time for Improvements
Make necessary renovations or updates to your new property before you move in. Painting, remodeling, or other improvements would be more challenging if you were already living there. Moving into a freshly updated home (instead of living in it during renovations) is just so much nicer!
Jumbo Mortgage Wins Using RSU & Equity Income
We help tech employees, executives, founders, and high-income professionals secure jumbo mortgages when traditional banks do not fully understand RSU income, stock grants, or pre-IPO equity. These files often require more than a standard approval process. We know how to document complex compensation, identify lenders that will consider eligible equity income, and build a loan profile strong enough to close high-value purchases in Austin, Houston, Dallas, Westlake, and beyond. These are real scenarios with names and identifying details changed for privacy.
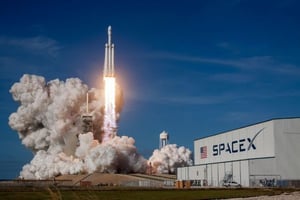
Purchasing a $2.7M Home in Austin using SpaceX Stock
The file: Borrower was purchasing a $2.7M home in Austin, Texas with a $2.4M mortgage. Multiple banks would not accept the borrower’s SpaceX equity because the stock had not been publicly traded for a full year.
What LendFriend did: We found a lender willing to review the private company equity, compensation history, liquidity, reserves, and overall borrower strength instead of automatically excluding the stock.
Outcome: Borrower was approved and closed on the Austin home using stock-based compensation that other lenders had rejected.
Databricks Employee Uses Pre-IPO Stock to Buy a Second Home in Dallas
The file: Borrower was buying a $1.6M second home in Dallas with a $1.44M jumbo mortgage at 90% LTV. The challenge was using pre-IPO equity in a high-LTV second home purchase.
What LendFriend did: We matched the borrower with an investor that accepted eligible pre-IPO stock and allowed a 90% LTV jumbo loan for the Dallas second home.
Outcome: Borrower secured financing with a jumbo loan option built around pre-IPO equity.
Meta Employee Closes on $2M Westlake Home in 14 Days
The file: Borrower was relocating from San Francisco to Westlake and purchasing a $2M home with a $400K down payment. The borrower had strong RSU income from Meta, but needed a lender that could close quickly and underwrite the equity compensation correctly.
What LendFriend did: We documented the RSU income clearly, matched the file with the right lender, and moved the approval process with urgency.
Outcome: Borrower closed on the Westlake home in 14 days using traditional RSU income.
ConocoPhillips Executive Buys $2.6M Houston Home With Recent Equity Grant
The file: Borrower was purchasing a $2.6M home in Houston with a $2.1M mortgage after receiving a large equity grant that had not yet vested. Most lenders would not count the equity because there was no vesting history.
What LendFriend did: We found a lender willing to evaluate the borrower’s executive compensation package, grant documentation, employment profile, income trajectory, liquidity, and overall financial strength.
Outcome: Borrower was approved for the Houston home despite having no vested equity history.
Want to buy a house using your RSUs to qualify for a mortgage?
Talk to Us About Your Options Today!
Why Tech Employees Trust LendFriend For Their Mortgage
LendFriend is an Austin-based mortgage broker that’s helped hundreds of tech professionals qualify using RSU income, whether they’re relocating to the fastest-growing tech hub in the U.S. or staying put in Silicon Valley, Los Angeles, or Denver.
We work with software engineers, developers, product managers, designers, and executives at public companies like:
-
Google
-
Meta
-
Amazon
-
Salesforce
-
Apple
-
Nvidia
-
SpaceX
-
AMD
Most lenders still underwrite based on outdated guidelines that don't reflect modern income. They want two years of W-2s, clean pay stubs, and income that fits neatly into a traditional box. That often leaves tech employees, executives, and startup employees with valuable equity compensation struggling to qualify for the home they can afford.
At LendFriend, we take a more modern approach. We help borrowers use RSUs for mortgage qualification, down payment strategy, or both, including employees at publicly traded tech companies and select pre-IPO companies where equity compensation plays a major role in total compensation.
We’ve helped employees from companies like Databricks, Anthropic, Ripple, Airtable, Ramp, and Stripe buy homes in Austin, Dallas, Houston and all across Texas using pre-IPO stock. Whether your RSUs are vested, vesting, publicly traded, or tied to a late-stage private company, LendFriend helps structure your loan around your real financial picture, not just what shows up on a standard pay stub.
What We Need to Document RSU Income
Lenders that accept equity compensation still want a clean paper trail. Having these items ready at the start shortens underwriting and keeps the file moving:
- Grant agreements and your current vesting schedule
- Two years of W-2s and recent pay stubs showing vested shares as income
- Brokerage or equity-plan statements confirming share counts and current value
- An employer letter covering your role, compensation structure, and future grants
- Sale confirmations and account statements if shares were sold for the down payment
Pre-IPO borrowers add a recent 409A valuation, tender offer or secondary sale records, and any liquidity timeline the company has shared with employees.
RSU Mortgages Across Key States
LendFriend helps tech employees, executives, and founders qualify with RSU income in several of the most competitive housing markets in the country.
In Texas, we work with employees of public companies and late-stage private companies across Austin, Dallas, and Houston who want their qualifying income to reflect vested stock rather than base salary alone.
For California homebuyers, equity compensation is often the largest part of total pay, and documenting it correctly is what makes a purchase in the Bay Area, Los Angeles, or San Diego possible.
We also help Florida borrowers relocating for a new role or buying a second home use vested RSUs for both qualifying income and down payment funds.
In Illinois, we work with Chicago and North Shore professionals whose RSU grants, bonuses, and commission income need to be counted together to support the right loan amount.
LendFriend also works with RSU-compensated borrowers buying and refinancing homes across Colorado, Virginia, and Maryland, including borrowers with recent grants, short vesting histories, or pre-IPO equity.
RSU income may be used for primary residences, second homes, and investment properties, as well as purchases, rate-and-term refinances, and cash-out refinances.
Keep Your RSUs. Buy The House. No Capital Gains Tax
At LendFriend, we work with types of clients with RSUs, including those whose wealth is tied up in equity, not base salary. If you’ve got millions in vested RSUs but a relatively low W-2, you’ve probably been told you “don’t qualify” for a mortgage.
That’s where we come in.
Instead of forcing you to sell shares and trigger capital gains, we may be able to help you leverage your RSU balance as an asset, similar to how we structure asset depletion loans. You keep your stock, maintain your investment position, and still qualify to buy the home you want.
It’s a smart solution for:
-
Early employees at IPO-stage companies
-
Tech execs with lopsided comp plans
-
Anyone whose liquid wealth lives in equity
We match you with lenders who understand modern compensation and structure your file to reflect your real financial picture.

BORROWER TESTIMONIALS
See Why Borrowers with RSUs Choose LendFriend Mortgage
See how employees with stock compensation, complex income, and nontraditional pay structures have worked with LendFriend Mortgage to secure financing with less stress and more certainty.
★★★★★
“John and team were very helpful. What could be an overly complicated process was quite simple with LendFriend.”
“LendFriend Mortgage delivered exceptional service to my husband and I with competitive rates, low fees, and a smooth, stress-free process.
Their team was professional, responsive, and incredibly knowledgeable, helping us first time home-buyers navigate everything for a conventional loan.
If you want a mortgage broker that’s trustworthy, efficient, and genuinely committed to your success, LendFriend is an outstanding choice.”
“Eric and his team were incredibly helpful and communicative throughout the lending and refinancing process, and made me feel very supported. Will definitely go back to them in the future.”
“Eric and his team at LendFriend were incredible. They helped us lock in a competitive mortgage rate and were super responsive — even on holidays!
Thanks to their speed and support, we were able to secure our dream home the same day it was listed.
I can’t recommend them enough. Really a great experience from start to finish!”
“We loved how nice and professional all of them are! They gave us the right information and orientation that we needed on every step! Thanks a lot!”
FAQs: How RSU Income Mortgages Work
Does RSU count as income for a mortgage?
Yes, many lenders will count vested RSU income as qualifying income, especially if you've received consistent stock grants for 1-2 years. At LendFriend, we work with lenders who understand RSU compensation and know how to document it properly.
Can pre-IPO RSUs help me qualify for a mortgage?
Yes, but private company RSUs are reviewed on an exception basis and are not treated the same way as RSUs from a publicly traded company. Because there is no daily public market price, lenders need to evaluate the strength of the company, the reliability of the valuation, the vesting schedule, and the likelihood that the equity can reasonably support the loan request.
Employees at strong private and pre-IPO companies may have more mortgage options than they realize. When RSUs are supported by a credible company valuation, meaningful investor backing, secondary market activity, tender offer history, or a clear path toward future liquidity, certain lenders may be willing to include them as part of the borrower’s overall qualification profile.
Private company RSUs require a more specialized review than publicly traded RSUs, but that does not mean they should be ignored. For borrowers with strong credit, stable employment, sufficient reserves, clean documentation, and equity from a well-capitalized private company, RSUs can sometimes help strengthen the loan file and expand what may be possible.
How do lenders calculate RSU income for a mortgage?
Most lenders average your vested RSU income over the past 24 months using pay stubs, W-2s, or tax returns, along with employer verification and supporting documents like grant schedules. Some use historical averages, while others project income from current stock values. In some cases we can use your grant schedule or an employer compensation letter to support a shorter income history.
Can I qualify for a mortgage if my base salary is low but I have a large amount of RSUs?
Absolutely. You can blend your salary and RSU income together. We specialize in working with clients whose wealth is tied up in equity, not just W-2 income. Our lenders often treat a large vested RSU balance much like an asset depletion loan, helping you qualify based on your full financial picture.
Can I use unvested RSUs to qualify for a home loan?
Typically, unvested RSUs are not counted as income. Some lenders will consider a percentage of unvested stock when reviewing RSU loan programs, provided there is strong documentation such as grant schedules, a signed offer letter, and employer verification. Vested shares carry more weight, but specialized programs allow both to support qualification. We review everything upfront to give you a clear path forward.
Do I need to sell my RSUs to qualify?
No. In some cases, we can help you qualify by treating RSUs as assets rather than income. This strategy can help you avoid capital gains events while still leveraging your equity.
Will selling RSUs affect my mortgage approval?
It can, depending on timing and documentation. Working with a lender like LendFriend that understands the RSU timeline lets you plan the sale, or avoid it altogether, before it becomes a problem in underwriting.
Can bonus or commission income be combined with RSU income?
Yes. Lenders can stack bonus income, commission, and vested RSU income on top of base salary as long as each source has a documented history, usually two years. Tech employees and executives with layered compensation often qualify for far more than their base salary alone would support.
What credit score do I need to get approved?
Most RSU mortgage programs require a credit score of 700 or higher, but every file is different. We’ve helped clients with complex income or credit profiles get approved by presenting their equity story the right way.
What's the minimum down payment required under an RSU mortgage?
RSU mortgages rely on whatever loan program you are utilizing (VA, conventional, jumbo, non-QM). Typically, lenders will require using a down payment of at least 10% when using RSU income on a jumbo loan, although if you are going conventional you can put as little as 3-5% down.
What mortgage options are available if part of my income comes from RSUs?
Borrowers with RSU mortgage options can choose from conventional loans, jumbo mortgages, portfolio lending, or non-QM programs. Each program evaluates stock-based income differently depending on vesting schedules and financial goals. The right option allows tech professionals to match their equity compensation with the most favorable lending terms.
What if a bank rejects my RSU income on a jumbo loan?
A denial from one bank is rarely the end of the file. Many banks apply narrow overlays to equity compensation, and there are alternatives when a bank rejects your income on a jumbo purchase. As a broker, we move the file to a lender that underwrites RSU income on its merits, often without restarting the timeline.
RSU Mortgage Learning Center
Our guides explain how lenders calculate RSU income, which loan programs accept vested and unvested shares, and how employees at public and pre-IPO companies have turned equity compensation into a home purchase.


Looking for other Tailored Non-QM Mortgage Solutions
RSU income is one of several ways LendFriend qualifies borrowers whose finances do not fit a standard W-2 file. If your strength sits in investment balances, business deposits, or credit and reserves rather than stock compensation, one of these Non-QM mortgage programs may be the better match.

Asset Depletion Mortgages
An asset depletion mortgage turns brokerage, retirement, and cash balances into qualifying income, so borrowers with substantial holdings and a modest W-2 can still qualify. Jumbo asset depletion loans apply the same method to higher-priced homes without selling a share.

Bank Statement Loans
Self-employed borrowers and business owners qualify on personal or business bank deposits in place of tax-return income. Jumbo bank statement loans bring the same deposit-based approach to larger loan amounts.

No-Ratio Loans
A no-ratio loan lets primary-residence buyers qualify with no debt-to-income calculation at all, relying on credit, equity, and reserves instead. Jumbo no-ratio loans carry that structure to larger primary residences.