Skip to content

Second Home Mortgages

Second home mortgage rates do not have to be meaningfully higher than primary residence rates. When the loan is structured correctly, many borrowers secure pricing close to what they would pay on the home they live in. LendFriend arranges second home purchases and cash-out refinances in 18 states, whether the property is a lake house, a beach home, a mountain retreat or a city condo.

Why Homebuyers Trust LendFriend With Their Second Home Mortgages

At LendFriend Mortgage, we specialize in second home mortgages across 18 states, from beach homes in Florida and the Carolinas to lake houses in Texas, Michigan and New Hampshire and mountain retreats in Colorado and Idaho. Many of our second home borrowers are in their 50s and 60s, self-employed or living on retirement income, and we structure the loan around how they earn and hold their wealth. We handle purchases and refinances, including cash-out refinances on second homes you already own.

Here is why borrowers work with us for their vacation and second homes:

Wide variety of loan programs. Second home financing is not one product. We arrange conventional fixed-rate loans, 5/6 and 7/6 ARMs, jumbo loans up to $10 million for higher-priced properties, bank statement loans for business owners whose tax returns understate their cash flow, and asset depletion loans for borrowers who qualify on their investments. Each is available for a purchase or a refinance.

Access to competitive pricing. Most lenders price second homes meaningfully higher than owner-occupied properties. Through select wholesale and portfolio options, including dedicated programs for second home mortgages in Texas, qualified borrowers may narrow that gap considerably.

Asset depletion loans for retirees and high-net-worth buyers. Borrowers with substantial brokerage and retirement accounts but limited traditional income may qualify using asset depletion loans, which convert eligible balances into qualifying income without selling the portfolio. We arrange them regularly for second homes in Naples, Sarasota and Palm Beach, Palm Desert and La Quinta, Pinehurst and Asheville, and Hilton Head and Kiawah Island.

Cash-out refinances on second homes. Owners with substantial equity in a vacation home may use a cash-out refinance to fund another purchase, a renovation or liquidity without selling investments. Bank statement loan and asset depletion loan documentation applies to a refinance the same way it applies to a purchase.

Second homes in retirement markets. Florida, California, North Carolina and South Carolina draw more second home buyers planning an eventual move than any other states we serve. Our Florida home loans cover The Villages, Vero Beach and Naples. In California we finance Palm Springs and the Coachella Valley. North Carolina buyers come to us for Pinehurst and the Brunswick County beaches. In South Carolina the demand is Bluffton, Hilton Head and Myrtle Beach. A second home today often becomes the primary residence later, and we plan for that at the start.

Strategic ARM and fixed options. A 30-year fixed is not always the best fit for a second home. 5/6 and 7/6 ARMs often deliver lower initial rates and can make sense if your expected ownership timeline is under 10 years.

RSU income for working buyers. For buyers still at companies like Apple, Nvidia and Meta, we work with lenders that factor RSU income into second home mortgage qualification.

Designed for lifestyle buyers, not investors. True second homes require different positioning than short-term rental or investment properties. We make sure the loan aligns with how you plan to use the property.

Experienced, trusted and proven. LendFriend has funded over $1.5 billion in home loans and earned 500+ five-star reviews, helping borrowers finance second homes in communities from Naples and Hilton Head to Palm Springs, Pinehurst, Lake Tahoe and the Texas Hill Country.

Loan Programs To Suit Every Second Home Buyer's Needs

LendFriend works with more than 40 wholesale lenders to arrange second home purchases and refinances, including cash-out refinances, for borrowers whose plans call for more flexibility than a single bank allows. Qualified borrowers may use conventional, ARM, jumbo, bank statement loan, asset depletion loan or RSU income options depending on how they earn and hold their wealth.

Conventional Second Home Loans

Conventional Second Home Loans

A conventional fixed-rate loan remains the most common way to finance a second home. We compare lenders whose second home pricing adjustments are smallest, so a 30-year fixed on a lake house or beach home may price close to a primary residence.

Learn More →

Jumbo Second Home Loans

Jumbo Second Home Loans

Higher-priced second homes in markets like Naples, Lake Tahoe and Aspen are purchased and refinanced with jumbo loans up to $10 million. We work with lenders offering competitive jumbo pricing and flexible reserve requirements depending on the borrower profile.

Learn More →

Bank Statement Loans

Bank Statement Loans

Business owners whose tax returns understate their cash flow may qualify with 12 or 24 months of personal or business deposits. Bank statement loans are available on second homes with the same occupancy standards as any other second home mortgage.

Learn More →

Asset Depletion Loans

Asset Depletion Loans

Retirees and high-net-worth borrowers with substantial investments but limited traditional income may qualify by converting eligible brokerage, retirement and cash balances into qualifying income, without selling the portfolio. The same documentation works for a purchase or a cash-out refinance.

Learn More →

RSU Mortgages

RSU Mortgages

Employees at companies like Apple, Nvidia, Meta and SpaceX often hold more of their compensation in restricted stock than in salary. We work with lenders that know how to count vested and vesting RSU income toward a second home purchase.
Learn More →

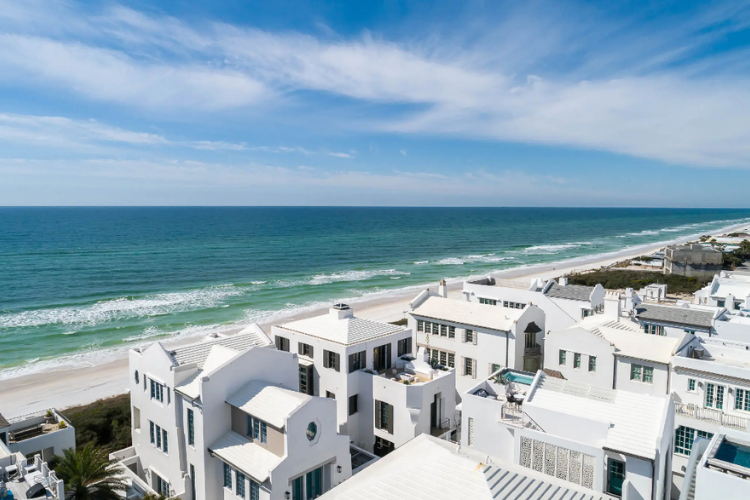
Beach homes in Alys Beach, Florida, financed as second homes

Straightforward Second Home Qualification

Financing a second home should not mean paying a dramatically higher rate if you are working with the right lender. With the right structure and the right lending partner, qualified borrowers may secure second home pricing close to a primary residence, on a purchase or a refinance. We make the process clear and straightforward from the start.

Clear expectations

We walk you through reserves, occupancy standards and how lenders define a second home, so you know exactly what qualifies before you write an offer or apply to refinance.

Access to better pricing

Most lenders have to add a rate adjustment on second homes. Wholesale and portfolio options can reduce that gap for well-qualified borrowers, which can make a meaningful difference in the monthly payment.

Smart loan options

Whether a fixed rate or an ARM makes more sense depends on how long you plan to keep the property. We help you choose based on your timeline, not guesswork. Self-employed borrowers may use jumbo bank statement loans at higher price points. Retirees may qualify through jumbo asset depletion loans.

Get Started on Your Second Home

Whether you are buying on the Gulf Coast, in the Rockies, on a New England lake, along the Carolina coast or in a New Jersey shore town, or refinancing a second home you already own, we structure the financing around how you use the property. Our where we lend page lists every state we serve.

From conventional second home loans to jumbo, portfolio and cash-out options, we help you compare your choices clearly and move forward with confidence. Apply online or speak with a second home loan expert today.

Westlake Austin House (2)
BORROWER TESTIMONIALS

See Why Borrowers Call Us the Best Mortgage Broker

From first-time homebuyers and business owners to jumbo borrowers and clients with complex income, see what borrowers across the country say about working with LendFriend Mortgage.

FAQs – Second Home & Vacation Home Mortgages

What qualifies as a second home?

A second home is a property you plan to occupy for personal use on a part-time basis, separate from your primary residence. To qualify, the home generally needs to be located a reasonable distance from your primary residence, be suitable for year-round occupancy, and not be subject to any agreement that requires it to be rented out.

Lenders evaluate how the property is intended to be used, not how it is labeled. Occasional rental use may be allowed depending on the loan program, but the property cannot function like a full-time investment property. You also need to qualify carrying both the primary home and the second home at the same time, which means income, reserves and overall financial profile matter more than they would on a primary residence purchase.

The key distinction is intent and usage. The line between a second home and an investment property decides which loan programs apply, even in vacation markets like the Florida coast, the Colorado mountains or the Texas Hill Country.

Are second home mortgage rates higher than primary residence rates?

In many cases, yes. Traditional conventional lenders typically price second homes higher than owner-occupied properties.

However, buyers may qualify for wholesale and portfolio options that significantly reduce that gap, and in some cases pricing can come close to a primary residence when the loan is structured correctly.

Credit profile, reserves, loan size and property type all influence final pricing.

What credit score is needed for a second home mortgage?

Most second home programs look for a minimum 700 credit score, and the lenders with the smallest second home pricing adjustments reserve them for well-qualified borrowers.

Borrowers with higher scores (720 to 740 and above) may receive the most competitive pricing and smoother underwriting, particularly when combined with sufficient reserves and stable income.

What is the maximum loan amount for a jumbo second home?

We arrange jumbo second home loans with loan amounts up to $10 million, subject to credit, income and reserve requirements.

Loan size, debt-to-income ratio, asset reserves and credit profile determine final approval and pricing. Because jumbo guidelines are set by each lender rather than by an agency, portfolio programs often provide more flexibility than agency jumbo second home options, particularly for properties in markets such as Naples, Palm Beach, Lake Tahoe, Vail, Hilton Head and other high-demand vacation areas.

Can self-employed buyers qualify for a second home mortgage?

Yes. Business owners whose tax returns understate their cash flow may qualify with 12 or 24 months of personal or business bank statements in place of tax returns.

Bank statement loans are available on second homes with the same occupancy standards as any other second home mortgage. We structure the file around deposits, reserves and property eligibility so the approval holds up in underwriting.

Can I do a cash-out refinance on a second home?

Yes. Owners of second homes refinance to pull equity for another property, a renovation, a business need or to keep investments in place rather than selling them.

Lenders price a second home cash-out refinance somewhat higher than a primary residence cash-out, and the same occupancy standards apply. Income can be documented with tax returns, bank statements or assets. For higher balances, a jumbo cash-out refinance follows the same path.

Can I rent out my second home?

Occasional short-term rental use may be allowed on some second home programs, but the property has to remain a personal-use home and cannot be financed on the strength of rental income.

If your main goal is rental income, the property is an investment property and belongs on a different loan. DSCR loans qualify on the rent the property is expected to produce rather than on your personal income.

Where are second homes popular in the states LendFriend serves?

Common second home markets include Naples, Palm Beach and the 30A beaches in Florida, Hilton Head and Charleston in South Carolina, the Outer Banks, Lake Tahoe, Palm Springs, Vail, Breckenridge and Sun Valley. Buyers also come to us for the Smoky Mountains, Lake Michigan, Lake Winnipesaukee, the Jersey Shore, the Eastern Shore of Maryland, the Oregon coast and the Texas Hill Country and Gulf Coast. Our ranking of the best places to buy a vacation home covers many of them.

Financing strategy can vary depending on property type, condo eligibility, flood zone designation and local market dynamics, especially in coastal markets where insurance and condo approval guidelines require closer review.

Why work with a mortgage broker for a second home?

Second home pricing adjustments vary widely between lenders. A mortgage broker compares wholesale lenders, portfolio options, jumbo programs and specialty structures to identify the most competitive solution for your scenario.

LendFriend has funded over $1.5 billion in home loans and earned 500+ five-star Google reviews. When you are structuring financing for a second property, experience directly affects the outcome.

The LendFriend Advantage for Second Home Buyers

At LendFriend Mortgage, second home mortgages are a core focus, not another option. We match buyers with the right lender based on the property, the loan size and the overall financial profile, with no hidden fees and a process built for speed. Whether you are buying a lake house, a mountain retreat or a coastal property, we keep the approval straightforward and the closing on track.

Around the Clock

We are available 7 days a week to help you compare second home mortgage rates, review lender options and move forward with confidence, whether you are buying a beach house, a lake house or a city condo.

Loan Options

We offer a full range of second home financing solutions, from conventional fixed rates to ARMs, jumbo loans, bank statement loans and asset depletion loans, so you get the right fit for your goals.

Get Pre-Approved Quickly

Our second home mortgage preapproval process strengthens your offer and gives sellers confidence in your ability to close. You can apply for a second home loan online in minutes.

Personalized Mortgage Guidance

You work one-on-one with a second home mortgage expert who explains your options, structures your file for approval and guides you through underwriting with clarity.

Close in as little as 14 days

Our process is built for larger transactions, so most second home loans close in as little as 14 days, even in competitive markets like Palm Beach, Austin and Lake Tahoe.

Learn More About Second Home Mortgages

Our Learning Center covers what second home buyers and owners ask most, from how lenders define a second home and price it against a primary residence to qualifying on assets or bank statements and pulling equity out with a cash-out refinance. Read some of our favorite second home articles below.

Contact us today to get a custom rate quote for your second home purchase or refinance in less than 2 minutes.