Skip to content

Jumbo Non-QM Loans in Pasadena, California

Pasadena and the San Gabriel Valley draw buyers looking for Craftsman homes, foothill estates and established neighborhoods close to Los Angeles. LendFriend offers jumbo Non-QM loans for borrowers whose income, assets or property call for more flexibility than a bank allows.

Why Homebuyers Trust LendFriend With Their Jumbo Loans in Pasadena and the San Gabriel Valley

A standard jumbo mortgage does not fit every high-value purchase in Pasadena or the San Gabriel Valley. LendFriend works with buyers of primary residences, second homes and investment properties, and we place loans through jumbo and jumbo Non-QM programs from more than 40 wholesale lenders.

We regularly help buyers finance homes in Pasadena, Arcadia, San Marino, La Cañada Flintridge and South Pasadena, where prices often run well above the conforming limit and income is not always simple to document.

Jumbo Loans Built Around the Borrower

Many buyers here qualify with salary income and savings. Others earn through a medical practice, an import business, rental property or an investment portfolio, and their tax returns may not show what they can afford.

LendFriend offers jumbo loans for each of these profiles, including:

  • Bank statement jumbo loans for eligible self-employed borrowers who qualify on 12 or 24 months of business or personal deposits in place of tax returns
  • Asset depletion jumbo loans for eligible borrowers who qualify on investment and retirement account balances
  • No-ratio jumbo loans for eligible borrowers financing a primary residence who qualify mainly on credit, equity and reserves, with no income calculation

Financing for Historic Homes and Foothill Estates

Pasadena and its neighbors attract buyers who want architecture and land. Purchases include Craftsman and period revival homes near the Arroyo Seco, estates in San Marino, hillside properties in La Cañada Flintridge and Bradbury, and newer, larger homes in Arcadia.

We help borrowers finance older homes, hillside lots and properties built for several generations of one family. Before we recommend a lender, we review the appraisal, the reserves, the occupancy and the source of the borrower's income.

A Faster, More Responsive Jumbo Process

Few homes come to market in San Marino, South Pasadena and La Cañada Flintridge, and good listings draw several offers. We review income, assets and credit before you write an offer and stay in contact with the lender, the appraiser and the escrow and title companies through funding. For a prepared borrower, a jumbo loan may close in as little as 14 days.

Trusted by Homebuyers

Thousands of homebuyers have trusted LendFriend with their financing, and more than 1,000 reviews speak to the service they received. Borrowers regularly praise our communication, speed, expertise and ability to find solutions when a loan is not straightforward.

Loan Programs To Suit Every San Gabriel Valley Borrower's Needs!

Our access to more than 40 wholesale lenders lets us arrange jumbo loan options with more flexibility than a single retail bank provides. Qualified buyers in Pasadena and the San Gabriel Valley may use bank statement loans, asset depletion loans, or crypto mortgages.

Asset Depletion Loans in Pasadena

Asset Depletion Loans in Pasadena

San Gabriel Valley retirees and investors can qualify on what they own with an asset depletion mortgage. Brokerage accounts, retirement funds, and savings may all be treated as income by the lender. High-net-worth buyers in San Marino and La Cañada Flintridge often use this loan when they no longer draw a salary.

Learn More →

Self Employed Mortgages in Pasadena

Self Employed Mortgages in Pasadena

A tax return rarely shows what a San Gabriel Valley business owner earns. We arrange self employed mortgage options for these owners that rely on deposits and require no tax returns or W-2s. Importers, physicians, and real estate investors in Arcadia, Walnut, Diamond Bar, and Glendale use these loans regularly.

Learn More →

Crypto Mortgages in Pasadena

Crypto Mortgages in Pasadena

Bitcoin and Ethereum holdings can support a home purchase through a crypto mortgage, and the borrower sells no tokens. Eligible buyers may qualify without employment income. A jumbo crypto mortgage can finance up to $5M for long-term holders buying in Pasadena, Arcadia, or Glendale.

Learn More →

RSU Mortgages For Corporate Employees in Pasadena

RSU Mortgages For Corporate Employees in Pasadena

Our RSU mortgage program counts vested Restricted Stock Units as income, so the borrower does not need to sell shares. The added income may raise the loan amount a salary alone supports. The program fits equity-compensated professionals at employers such as Edison International in Rosemead and East West Bancorp and Alexandria Real Estate Equities in Pasadena.

Learn More →

Buy Before You Sell in Pasadena

Buy Before You Sell in Pasadena

Owners who need to move before selling can use our Buy Before You Sell program. The purchase is funded with a bridge loan secured by the equity in the current home. Eligible borrowers may apply current home equity toward the next down payment and make a non-contingent offer. The existing home can then be listed after the move.

Learn More →

Jumbo No-Ratio Loans in Pasadena

Jumbo No-Ratio Loans in Pasadena

Buy or refinance a primary residence above the conforming limit with no debt-to-income calculation. A no-ratio loan is approved on credit, equity, reserves, and mortgage history, which suits owners in Pasadena whose wealth sits in real estate or a business and not on a tax return.
Learn More →

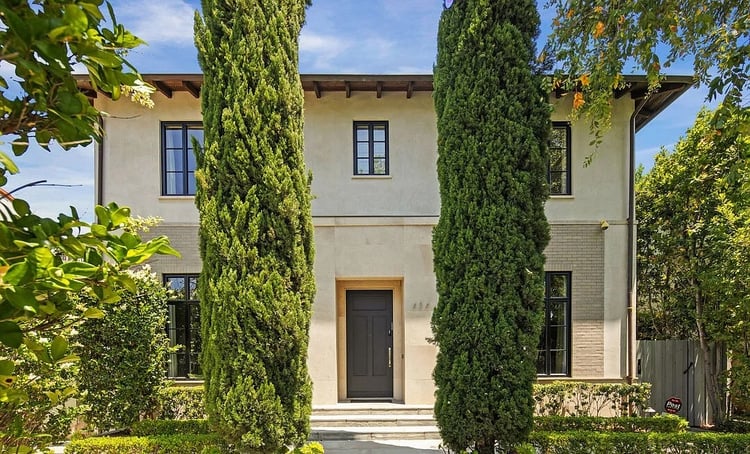
Luxury home near Pasadena, California

Straightforward Qualification That Works for Buyers in Pasadena, Arcadia and San Marino

Buyers in Pasadena, Arcadia, San Marino and La Cañada Flintridge often ask what a lender needs to see for a jumbo loan. We look at credit, income, assets, reserves and the property before you apply, so you know which programs are open to you.

Clear qualification guidelines for jumbo loans

We state the credit score, debt-to-income, reserve and documentation standards for each loan at the start, so your budget rests on real numbers.

More options for self-employed and retired buyers

LendFriend offers jumbo bank statement loans for eligible business owners and 1099 earners, and jumbo asset depletion loans for retirees and investors who qualify on eligible brokerage and retirement accounts.

Get Started On Your Pasadena Jumbo Loan

You may be buying a Craftsman home near the Arroyo Seco, an estate in San Marino or a hillside property in La Cañada Flintridge. In each case, LendFriend can help you find a home loan in California suited to your income and assets.

Apply online or schedule a call with our team. We will go over your loan options, current jumbo mortgage rates and the documents a lender will ask for. Eligible borrowers may also be set up for a short escrow once an offer is accepted.

Home in the Pasadena & San Gabriel Valley area of California

Jumbo Non-QM Loan Examples for Pasadena and San Gabriel Valley Buyers

Business owners, physicians, investors and retirees in the San Gabriel Valley often pair a seven-figure loan with income that is hard to document. The four scenarios below are illustrative examples of how lenders can structure jumbo loans for California homes using asset depletion loans, bank statement loans and jumbo no-ratio loans, for a purchase or a cash-out refinance. A jumbo no-ratio loan is available for a primary residence only.

$2.6M Asset Depletion Loan in San Marino

A retired physician and his spouse are buying a $4M home near the Huntington Library in San Marino and hold $9M in brokerage and IRA accounts. A jumbo asset depletion loan can count those balances as qualifying income for a $2.6M mortgage. The buyers put $1.4M down, or 35%, and leave the rest of the portfolio invested.

$2.8M Cash-Out Asset Depletion Loan in La Cañada Flintridge

A La Cañada Flintridge couple owns a home worth about $5M with a $1.1M mortgage and wants cash to buy a second property. A jumbo asset depletion loan can qualify a $2.8M cash-out refinance on an $11M investment portfolio, with no employment income documented. The new loan equals 56% of value and returns about $1.7M to the owners before closing costs.

$2.1M Bank Statement Loan in Arcadia

The owner of an import company is buying a $2.8M home in Arcadia, and her tax returns show far less than her $95,000 in average monthly deposits. A jumbo bank statement loan can qualify a $2.1M mortgage on 12 months of business deposits. She puts $700,000 down, or 25%, and no tax returns go into the file.

$2.4M Cash-Out No-Ratio Loan in Pasadena

A Pasadena owner holds a primary residence in the Oak Knoll neighborhood worth about $4.2M with a $1.2M mortgage. A jumbo no-ratio loan, offered for a primary residence only, can support a $2.4M refinance on credit, equity, reserves and mortgage history. The refinance releases about $1.2M at 57% of value, and the lender calculates no debt-to-income ratio.

Jumbo Mortgage Options Beyond Pasadena

Buyers in Pasadena and the San Gabriel Valley frequently own or plan to own property in a second market. A job change, a vacation home, or a move closer to family can each prompt the search. LendFriend arranges jumbo financing in many of the places these buyers look.

In California, our lending covers higher-priced homes from San Marino and Arcadia to the coast and the Bay Area. We arrange jumbo loans in California for luxury primary residences, second homes, and investment properties statewide.

Closer to home, buyers compare the foothills with Los Angeles neighborhoods such as Los Feliz, Hancock Park, and Brentwood. West of Glendale, others consider Studio City, Encino, and Calabasas in the San Fernando Valley. Buyers who want the coast look at Manhattan Beach and the Palos Verdes Peninsula in the South Bay. Families from Arcadia, Walnut, and Diamond Bar often shop Orange County cities such as Irvine and Newport Beach. Others relocate to the Bay Area for technology careers or retire to San Diego coastal communities such as Del Mar and Coronado.

We also work with buyers leaving California for Texas, where Dallas and Houston attract corporate relocations. Mountain and lake second homes lead other clients to Boise and Sun Valley in Idaho, Bend in Oregon, and the ski towns of Colorado.

We can compare jumbo mortgage options with you before you write an offer in Pasadena, elsewhere in Southern California, or in another state.

BORROWER TESTIMONIALS

See Why Jumbo Borrowers Choose LendFriend Mortgage

See how homebuyers across the country have worked with LendFriend Mortgage to navigate larger loan amounts, complex income, and jumbo mortgage financing.

FAQs – Getting a Jumbo Loan In Pasadena

What loan amount qualifies as a jumbo loan in Pasadena and Los Angeles County?

The 2026 conforming loan limit for a one-unit property in Los Angeles County is $1,249,125. Lenders treat any mortgage above this figure as a jumbo loan.

Pasadena and every other San Gabriel Valley city sit in Los Angeles County, and the 2026 limits are:

  • Single-unit property: $1,249,125

  • Two-unit property: $1,599,375

  • Three-unit property: $1,933,200

  • Four-unit property: $2,402,625

Prices in San Marino, La Cañada Flintridge, Arcadia, and Pasadena regularly exceed these limits, and most higher-priced purchases in these cities are financed with jumbo mortgages.

How much can I borrow with a jumbo loan in Pasadena?

Loan amounts for well-qualified buyers of jumbo loans in California can run to several million dollars. The lender sets the maximum from the credit score, the loan-to-value ratio, and the reserves in the file. Better credit and more reserves tend to produce lower rates and stronger terms.

Do jumbo loans require perfect credit?

No. Scores of 750 and higher earn the best jumbo pricing. A borrower below that level may still qualify when a larger down payment or substantial liquid assets offset the score.

Can I get a jumbo loan in Pasadena if I am self-employed or have complex income?

Yes. Our Jumbo Non-QM programs for San Gabriel Valley buyers include bank statement loans and asset depletion loans. Business owners, investors, and retirees buying in Arcadia or San Marino may qualify without W-2s or standard tax returns. A jumbo bank statement loan uses 12 or 24 months of deposits to calculate income, and loan amounts reach $7M. Digital asset holders have a further option, since crypto mortgages for a California home qualify the borrower on Bitcoin and Ethereum holdings.

What property types are eligible for jumbo financing in Pasadena?

Lenders offer jumbo financing on single-family homes, condos, townhomes, and two- to four-unit properties. We arrange loans for a Craftsman estate in Pasadena, a San Marino residence, an Old Pasadena condo, or a hillside home in Glendale. Condo approval turns partly on the building, and the rules differ for warrantable and non-warrantable condos.


How do jumbo loan interest rates compare to conventional rates in Pasadena?

Jumbo pricing in the San Gabriel Valley often sits near conventional rates and occasionally below them. Well-qualified borrowers in markets such as San Marino and La Cañada Flintridge attract strong competition among lenders.

Is an adjustable-rate mortgage a good option for a jumbo loan in Pasadena?

An ARM may suit a borrower who expects to hold the loan for a limited number of years. The rate on a 5/1 or 7/1 jumbo ARM is fixed for five or seven years and usually starts below a 30-year fixed rate. On an Arcadia or South Pasadena purchase, the monthly savings in the fixed period can be substantial. Lower starting rates explain why ARMs are back for jumbo borrowers. The plan for the home matters as well, including whether an ARM fits a borrower who plans to sell soon.

How much equity can I access with a jumbo cash-out refinance in Pasadena?

A jumbo cash-out refinance pays off the current mortgage with a larger jumbo loan and gives the owner the difference in cash. Maximum loan-to-value is typically about 80% on a primary home, and lenders reduce it on very large loan amounts. Credit, reserves, and the appraised value determine the amount available to owners in Pasadena, San Marino, and Arcadia. Homeowners with VA entitlement may reach a higher loan-to-value through a VA cash-out refinance or a VA jumbo cash-out refinance, and neither loan has monthly mortgage insurance.

Can I use a VA loan for a jumbo purchase in Pasadena?

A VA loan can exceed the conventional limit for eligible veterans and active-duty service members buying in the San Gabriel Valley. Qualified borrowers may purchase a higher-priced home in Pasadena or Glendale with $0 down and no monthly PMI. A borrower with full entitlement may use VA jumbo loans without a set loan limit.

Can I refinance a jumbo loan in Pasadena?

Yes. Owners use a jumbo refinance to reduce the rate, move from an adjustable loan to a fixed one, or take cash from equity. The rules for a California cash-out refinance depend on occupancy, credit, and loan size.

What can I do if a bank denied my jumbo loan in Pasadena?

Banks apply their own overlays on top of standard jumbo guidelines, so a denial at one institution does not settle the question. Wholesale lenders differ in how they count bonus income, RSUs, business income, and large asset balances. As a broker, we can resubmit the same file to a lender whose rules fit the borrower. Buyers still have several alternatives for California jumbo loans after a bank rejects their income documentation. A purchase in escrow can often be saved after a jumbo loan denial.

How much do I need to put down on a jumbo loan in Pasadena?

A down payment of 10% to 20% is typical for a jumbo loan on a primary residence in the San Gabriel Valley. The 10% options are limited to borrowers with strong credit and reserves. Second homes and investment properties generally call for a larger down payment. Program, occupancy, and loan amount all affect jumbo and Non-QM mortgage down payments, and lenders also verify reserves after closing. Escrow, title, and lender fees are separate from the down payment and make up most closing costs in California.

Why Choose LendFriend?

LendFriend Mortgage treats jumbo loans in the San Gabriel Valley as a primary line of business. We select a jumbo lender for each borrower based on the property, the borrower's finances, and the reason for the loan. Fees are disclosed in advance, and the process is organized to close quickly. Buyers in Pasadena and the San Gabriel Valley can choose a 30-year fixed loan, a 7/1 ARM, or a flexible Non-QM option.

Around the Clock

Our loan officers are available 7 days a week to review jumbo mortgage rates and lender choices. We lend on primary residences, second homes, and investment properties.

Loan Options

Pasadena borrowers can choose among conventional fixed-rate jumbo loans, ARMs, bank statement loans, and asset depletion loans. The right loan depends on how you earn income and how long you plan to own the property.

Get Pre-Approved Quickly

Pasadena sellers give more weight to an offer backed by a jumbo preapproval. The online application for a jumbo loan takes minutes, and we review it promptly.

Personalized Mortgage Guidance

A jumbo mortgage expert handles your loan personally, explains the options, organizes the file for approval, and stays with it through underwriting.

Close in as little as 14 days

Larger transactions are our daily work, and many jumbo loans close in as little as 14 days in competitive markets such as Pasadena, Arcadia, San Marino, and La Cañada Flintridge.

Contact us today to get a custom rate quote for your Pasadena home financing in less than 2 minutes.