“Super impressed with how fast and smooth the whole process was — especially given my complex RSU comp structure that traditional banks kept discounting.
Eric and the team had no problem including my full base + RSU compensation. They were extremely fast, set clear expectations from the start, and followed through on everything they promised.
Honestly one of the easiest and most stress-free mortgage experiences I’ve ever had. Highly recommend!”
Mortgage Broker in the San Fernando Valley for Jumbo Non-QM Loans
We are a mortgage broker for buyers in Sherman Oaks, Encino, Studio City, Calabasas, and the rest of the San Fernando Valley. We compare jumbo rates and guidelines from more than 40 wholesale lenders for self-employed buyers, entertainment professionals, retirees, and purchasers of high-value homes.
Why Homebuyers Trust LendFriend With Their Jumbo Loans in the San Fernando Valley
Jumbo mortgages make up a large share of the loans we arrange at LendFriend Mortgage. We finance high-value homes across the San Fernando Valley, including primary residences, second homes, and investment properties. A purchase may be a gated estate in Hidden Hills, a hillside home south of Ventura Boulevard in Encino, or a newer build in Studio City. Our Valley loans are priced across more than 40 wholesale lenders. Some Valley buyers also bid over the hill in Brentwood and Beverly Hills, where higher prices often call for larger loans and deeper reserves.
Our jumbo options include 30-year fixed mortgages, adjustable-rate mortgages (ARMs), and Non-QM loan programs for borrowers whose income or assets do not match traditional guidelines.
More Than a 30-Year Fixed Jumbo Loan
A 30-year fixed loan is the default choice, and some Valley borrowers are better served by another structure. A buyer who plans to sell, refinance, or change neighborhoods within a few years may consider a jumbo ARM. 5/1 and 7/1 adjustable-rate mortgages can start with a lower rate and a smaller monthly payment.
We help Valley buyers compare the choices against how long they expect to own the home, the loan amount, and their long-term finances.
Jumbo Loans for Self-Employed and Retired Buyers
Income in the San Fernando Valley often comes from production companies, medical practices, royalties, and investment accounts instead of a W-2. Business owners, retirees, executives, and high-net-worth buyers may have strong cash flow and assets but report less income than a conventional jumbo lender asks for.
Several jumbo loan options exist for these Valley borrowers, including:
-
Bank statement loans that qualify eligible self-employed buyers and business owners on 12 or 24 months of deposits instead of tax returns
-
Asset depletion loans that allow eligible retirees and high-net-worth borrowers to qualify on investment and retirement account balances
Either program may support a larger loan amount than tax returns alone would allow.
Competitive Jumbo Rates and Loan Options
A small difference in rate adds up to a large sum over the life of a seven-figure mortgage. We compare jumbo lenders for San Fernando Valley buyers across loan sizes, down payments, property types, and borrower profiles.
We review loan-to-value, reserves, credit, income, assets, and the expected holding period before we recommend a loan for a Valley purchase.
Fast Jumbo Closings for San Fernando Valley Homebuyers
Homes in Sherman Oaks, Studio City, and Encino often receive several offers in the first week on the market. Our team works with buyers, real estate agents, escrow officers, title companies, appraisers, and lenders throughout the transaction. Many jumbo loans for Valley buyers can close in as little as 14 days.
A shorter escrow may help Valley buyers compete with cash offers without giving up competitive financing.
Loan Programs To Suit Every San Fernando Valley Borrower's Needs!
LendFriend works with more than 40 wholesale lenders and arranges jumbo loan options for buyers who need more flexibility than one bank can offer. Qualified San Fernando Valley borrowers can choose among bank statement loans, asset depletion loans, and crypto mortgages.

Asset Depletion Loans in the San Fernando Valley
An asset depletion mortgage converts brokerage accounts, retirement funds, and savings into qualifying income for a home purchase. The borrower keeps the accounts invested. This loan suits high-net-worth buyers in Encino and Calabasas whose income does not come from a W-2.

Self Employed Mortgages in the San Fernando Valley
Business owners often show less taxable income than they earn. We arrange self employed mortgage options for Valley owners that qualify on deposits, with no tax returns or W-2s required. These loans serve production company owners, physicians, and contractors across Sherman Oaks, Woodland Hills, Burbank, and the rest of Los Angeles County.

Crypto Mortgages in the San Fernando Valley
A crypto mortgage lets eligible borrowers buy a home on Bitcoin and Ethereum holdings without selling a token. Employment income is not part of the qualification. Long-term holders buying in Studio City, Tarzana, or Calabasas can finance up to $5M through a jumbo crypto mortgage.

RSU Mortgages For Entertainment and Biotech Employees in the San Fernando Valley
Studio and biotech employees can count vested Restricted Stock Units as mortgage income and keep their shares. Our RSU mortgage program adds stock grants to base salary. Equity-compensated professionals at employers such as The Walt Disney Company in Burbank, Comcast's NBCUniversal in Universal City, and Amgen in Thousand Oaks may qualify for a larger loan.

Buy Before You Sell in the San Fernando Valley
Our Buy Before You Sell program lets eligible owners purchase the next home before the current one is sold. Financing comes from a bridge loan on the current residence, which is paid off at its sale. Equity in a Sherman Oaks or Encino home may fund the down payment, and the offer carries no sale contingency. The two transactions can then close on separate dates.

Jumbo No-Ratio Loans in the San Fernando Valley
No debt-to-income ratio is calculated on a no-ratio loan. Lenders review credit, equity, reserves, and mortgage history on a primary residence above the conforming limit. The loan may serve owners in the San Fernando Valley whose wealth does not appear as taxable income.
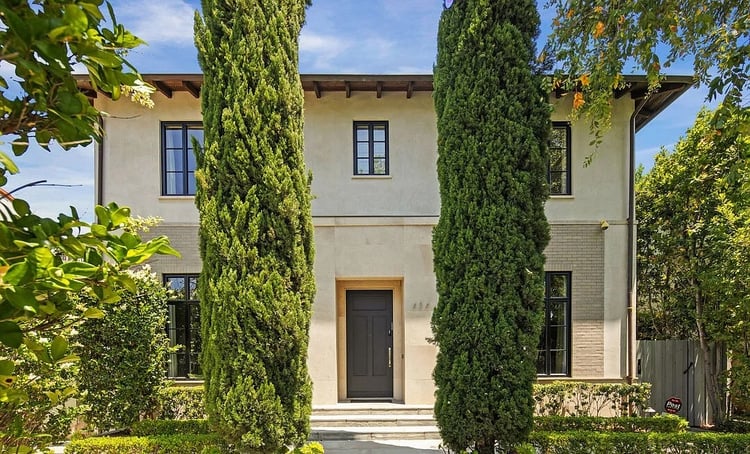
Straightforward Qualification That Works for Buyers in Sherman Oaks, Encino and Calabasas
Many buyers want to know what it takes to qualify for a jumbo loan in Sherman Oaks, Encino, Woodland Hills, or Calabasas. We explain the requirements at the start.
Transparent income, credit & DTI guidelines
We go through the credit score, documentation, and debt-to-income requirements for each jumbo loan before you make an offer.
Flexible solutions for self-employed professionals and retirees
A W-2 salary is one of several ways Valley buyers qualify. We arrange self-employed jumbo loans and asset depletion loans in California for entrepreneurs, investors, and retirees financing high-value homes in Hidden Hills, Tarzana, and the hillside streets south of Ventura Boulevard. Retirees who sell in the Valley and move south to La Jolla or Del Mar may qualify on the same account balances.
Ready When You Are – Let's Get Started
We structure jumbo mortgages for buyers of a Hidden Hills equestrian estate, a Royal Oaks home in Encino, a Longridge Estates residence in Sherman Oaks, or a gated home in The Oaks of Calabasas. Valley financing ranges from 10% down jumbo loans for strong files to specialty Non-QM solutions for self-employed and retired buyers. Owners who keep a second home on the coast in Newport Beach or Laguna Beach can finance both properties through us.
Apply for a jumbo loan online today or speak with a loan officer who knows the Valley. We will compare current jumbo mortgage rates in California, explain how jumbo loans differ from conforming mortgages, and outline the steps to closing. Many of our clients in Sherman Oaks, Encino, Studio City, and Calabasas close in as little as 14 days.
Jumbo Non-QM Loan Examples for San Fernando Valley Buyers
Producers, business owners, executives, and retirees across the San Fernando Valley often need a large loan and have income a bank cannot easily document. These illustrative examples show how jumbo loan options for high-net-worth California borrowers, including asset depletion loans, bank statement loans, and jumbo no-ratio loans, can be structured. Lenders make the jumbo no-ratio loan for a primary residence only.
$3.1M Asset Depletion Loan in Encino
A retired couple buying a $4.5M home in the Royal Oaks section of Encino prefers to leave a $12M portfolio invested. A jumbo asset depletion loan can turn brokerage and retirement balances into qualifying income for a $3.1M mortgage. The couple can close with about 31% down and sell no securities.
$2.8M Cash-Out Asset Depletion Loan in Calabasas
A retired studio executive owns a $5.6M home in The Oaks of Calabasas with a $1.2M mortgage and wants to draw on the equity. A jumbo asset depletion loan can count an $8M brokerage and retirement portfolio as qualifying income for a $2.8M cash-out refinance. The new loan equals 50% of the home's value and can return about $1.6M in cash before closing costs.
$2.5M Bank Statement Loan in Sherman Oaks
The owner of a post-production company is buying a $3.2M home in Sherman Oaks and shows modest taxable income after equipment write-offs. A jumbo bank statement loan can qualify a $2.5M mortgage on 24 months of business deposits instead of tax returns. The buyer puts roughly 22% down and can close within a 30-day escrow.
$3M Cash-Out No-Ratio Loan in Hidden Hills
An entrepreneur owns a $7.6M primary residence in Hidden Hills with a $2M mortgage and keeps most of her net worth in a private company. A jumbo no-ratio loan, available for a primary residence only, can support a $3M cash-out refinance based on equity, credit, and mortgage history. The loan stays near 40% of value, and the lender calculates no debt-to-income ratio.
Jumbo Mortgage Options Beyond the San Fernando Valley
Valley buyers often look past the 101 and 405 corridors when they shop for a home. Some are moving closer to work, some are adding a beach or mountain property, and others are leaving California. We arrange jumbo financing in many of the markets Valley households consider.
Within California, we finance higher-priced homes from Calabasas and Encino to the Central Coast and the desert. Our jumbo loans in California are available for luxury primary residences, second homes, and investment properties across the state.
Many searches cross the hill to the Westside of Los Angeles. Other buyers move south to the Orange County and San Diego coasts, and technology careers take some Valley households north to the Bay Area.
Outside California, we work with buyers relocating to Texas, including Austin and Dallas, and to Tennessee, where Nashville and Franklin draw entertainment professionals. Second-home buyers from the Valley often choose Idaho markets such as Sun Valley and Coeur d'Alene or Colorado resort towns such as Aspen and Telluride.
Whether the next home is in the San Fernando Valley, elsewhere in Southern California, or in another state, we can help you compare jumbo mortgage options before you make an offer.
BORROWER TESTIMONIALS
See Why Jumbo Borrowers Choose LendFriend Mortgage
See how homebuyers across the country have worked with LendFriend Mortgage to navigate larger loan amounts, complex income, and jumbo mortgage financing.
★★★★★
“Eric is my go to guy for all lending needs. This is my third time with Lendfriend and will be back for future purchases and refi!”
“The team at LendFriend made buying our home in Florida so easy. We had an expiring lease and LendFriend was able to move very quickly to get us closed in under 30 days before the lease ended.
They also got us a great rate on a jumbo loan and were available day and night to answer all of our questions. If you’re looking for a mortgage broker that makes the process stress-free while still getting you a great rate, you have to call LendFriend.”
“We had a great experience working with LendFriend, specifically, Michael and team. They were responsive, knowledgeable, and professional throughout the entire process. Communication was clear, and they made everything feel smooth and easy.”
“LendFriend is the absolute best. I found them after I was denied by a lender due to an appraisal issue. I spoke with dozens of lenders, but LendFriend was the only one that could figure out a solution.
They were able to close my jumbo loan in less than 3 weeks and hit my closing date. If you need a lender to step in and save the day, call LendFriend!”
“The staff from my new favorite mortgage company Lendfriend is the best experience I’ve ever had from any lending organization...Their customer Service was very attentive and always prepared to assist me in every way...Ask for Eric !!”
FAQs – Getting a Jumbo Loan In the San Fernando Valley
What loan amount qualifies as a jumbo loan in the San Fernando Valley and Los Angeles County?
In Los Angeles County, the 2026 conforming loan limit for a one-unit property is $1,249,125. A mortgage above this amount is a jumbo loan.
The 2026 limits for Los Angeles County, which covers nearly all of the San Fernando Valley, are listed below:
-
Single-unit property: $1,249,125
-
Two-unit property: $1,599,375
-
Three-unit property: $1,933,200
-
Four-unit property: $2,402,625
Bell Canyon sits in Ventura County, where the one-unit limit is $1,035,000. Homes in Sherman Oaks, Encino, Studio City, and Calabasas regularly sell above these thresholds, so jumbo mortgages are the standard financing in these neighborhoods.
How much can I borrow with a jumbo loan in the San Fernando Valley?
Strong borrowers can obtain jumbo loans in California well into the multi-million range. Lenders base the approval on credit score, loan-to-value ratio, and reserves. Higher credit scores and deeper reserves usually bring lower jumbo rates and better terms.
Do jumbo loans require perfect credit?
No. A score of 750 or above helps a borrower obtain the best jumbo pricing. Borrowers with lower scores may still qualify if the file shows offsetting strengths, such as a larger down payment or significant liquid assets.
Can I get a jumbo loan in the San Fernando Valley if I am self-employed or have complex income?
Yes. We arrange Jumbo Non-QM programs for Valley buyers, including bank statement loans and asset depletion loans. Producers, practice owners, and retirees buying in Sherman Oaks or Encino may qualify without W-2s or traditional tax returns. Jumbo bank statement loans calculate income from 12 or 24 months of deposits and reach loan amounts up to $7M. Several alternatives for California jumbo loans remain available when a bank rejects the income documentation.
What property types are eligible for jumbo financing in the San Fernando Valley?
Jumbo financing is available for single-family homes, townhomes, properties with two to four units, and warrantable and non-warrantable condos. We arrange loans for a Hidden Hills estate, a Studio City hillside home, a Woodland Hills view property, or a Toluca Lake residence.
How do jumbo loan interest rates compare to conventional rates in the San Fernando Valley?
Jumbo rates in the San Fernando Valley are frequently in line with conventional rates and can be lower. Lenders compete for well-qualified jumbo borrowers in established neighborhoods such as Encino and Sherman Oaks.
Is an adjustable-rate mortgage a good option for a jumbo loan in the San Fernando Valley?
It can be, and the answer depends on the expected holding period. A jumbo ARM in the 5/1 or 7/1 form holds its rate for five or seven years and often prices under a 30-year fixed loan. The lower starting payment matters on a Studio City or Calabasas purchase, which is one reason ARMs have regained favor with jumbo borrowers. Buyers who expect to move or refinance within the fixed period are the usual candidates. Technology employees who expect a transfer to San Francisco or Silicon Valley within several years may prefer this structure. Each borrower should also weigh whether an ARM is a sound choice ahead of a sale.
How much equity can I access with a jumbo cash-out refinance in the San Fernando Valley?
Most jumbo lenders cap a cash-out refinance near 80% of value on a primary home, and the cap falls as the loan amount rises. Credit, reserves, and the appraisal all affect the final figure. Owners in Encino, Tarzana, and Woodland Hills can draw on their equity through a jumbo cash-out refinance. The new loan replaces the current mortgage and pays out the difference. Valley homeowners with VA entitlement may be able to borrow a higher share of value with a VA cash-out refinance or a VA jumbo cash-out refinance. Neither of these VA loans adds monthly mortgage insurance to the payment.
Is a VA loan an option for a jumbo purchase in the San Fernando Valley?
Eligible veterans and active-duty service members may be able to use a VA loan above the conventional limit in Los Angeles County. Qualified borrowers may buy a higher-priced Valley home with $0 down and no monthly PMI. For borrowers with full entitlement, VA jumbo loans may have no fixed loan limit.
Can I refinance a jumbo loan in the San Fernando Valley?
Yes. A jumbo refinance can lower the rate, replace an ARM with a fixed loan, or convert equity in a high-value home to cash. Self-employed owners can also use refinancing options for California business owners that qualify income from deposits.
What can I do if a bank denied my jumbo loan in the San Fernando Valley?
One bank's denial usually reflects that bank's internal overlays and says little about the borrower's ability to qualify elsewhere. Wholesale jumbo lenders each treat bonus income, RSUs, residuals, business income, and large asset balances differently. A broker can take the file to a different lender with guidelines that fit residual or stock income. Buyers already in escrow still have several options when a jumbo loan is denied.
How much do I need to put down on a jumbo loan in the San Fernando Valley?
Jumbo lenders generally require 10% to 20% down on a primary residence in Los Angeles County. Borrowers with the strongest credit and reserves receive the lowest down payment options, and second homes and investment properties usually need more. Reserves that remain after the close of escrow also count. Down payment requirements for jumbo and Non-QM mortgages vary by program, occupancy, and loan size. Buyers should also budget for average closing costs in California, which include escrow and title fees.
Why Choose LendFriend?
Jumbo lending for San Fernando Valley buyers is a core specialty at LendFriend Mortgage. We pair each Valley borrower with a jumbo lender chosen for the property, the financial profile, and the goal of the loan. Our process carries no hidden fees and is built to move quickly. We arrange 30-year fixed loans, 7/1 ARMs, and flexible Non-QM options for buyers throughout the San Fernando Valley.
Around the Clock
We work 7 days a week to compare jumbo mortgage rates and lender options for you. Valley primary homes, second homes, and investment properties are all eligible.
Loan Options
San Fernando Valley buyers can choose conventional fixed rates, ARMs, bank statement loans, or asset depletion loans. We recommend a loan based on your income, assets, and plans for the home.
Get Pre-Approved Quickly
A jumbo preapproval shows a seller that you can close on a higher-priced home and strengthens your offer. The online jumbo loan application takes a few minutes from start to finish.
Competitive Rates with No Points
We shop several jumbo lenders for competitive rates on your profile and avoid unnecessary points and hidden charges.
Personalized Mortgage Guidance
You work directly with a jumbo mortgage expert who explains each option, prepares the file for approval, and manages underwriting.
Close in as little as 14 days
Our process is built for larger transactions, and many jumbo loans close in as little as 14 days in competitive markets such as Sherman Oaks, Encino, Studio City, and Calabasas.