Skip to content

Jumbo Non-QM Loans in Santa Barbara, California

Santa Barbara, Montecito and the Santa Ynez Valley attract buyers purchasing ocean-view estates, Riviera hillside homes and ranch properties near Los Olivos and Santa Ynez. LendFriend offers jumbo Non-QM financing, including asset depletion loans for borrowers with substantial investment portfolios and bank statement loans for self-employed buyers, with more flexible qualification options than many conventional banks provide.

Why Homebuyers Trust LendFriend With Their Jumbo Loans in Santa Barbara

Many purchases in Santa Barbara County above the conforming limit involve a borrower, a property or both that a standard jumbo lender handles poorly. LendFriend works with buyers of primary residences, second homes and investment properties and places loans through jumbo and jumbo Non-QM programs from more than 40 wholesale lenders.

We regularly help buyers finance homes in Santa Barbara, Montecito, Hope Ranch, Carpinteria, Goleta and the Santa Ynez Valley, where high values, portfolio income and acreage can make a lender's guidelines harder to meet.

Jumbo Loans Built Around the Borrower

Salary and savings carry some buyers through underwriting with ease. A founder who sold a company, a winery owner or a retiree living on investments often has the means but not the tax return a bank wants to see.

LendFriend offers jumbo financing for these borrowers and others, including:

  • Bank statement jumbo loans for eligible self-employed borrowers who qualify on 12 or 24 months of business or personal deposits with no tax returns required
  • Asset depletion jumbo loans for eligible borrowers whose qualifying income comes from investment and retirement accounts
  • No-ratio jumbo loans for eligible borrowers purchasing or refinancing a primary residence on the strength of credit, equity and reserves, without an income calculation

Financing for Estates, Ocean-View Homes and Valley Ranches

The South Coast and the Santa Ynez Valley attract buyers with specific properties in mind. A Montecito estate, a Hope Ranch equestrian property, a Riviera home with an ocean view or a vineyard parcel near Los Olivos each brings its own appraisal and lender questions.

We help borrowers finance large lots, agricultural parcels, older homes and second homes in Santa Barbara County while accounting for occupancy, reserves and the way each borrower's wealth is held. The lender is chosen for the property as much as for the file.

A Faster, More Responsive Jumbo Process

Inventory in Montecito, Hope Ranch and the Santa Ynez Valley stays thin, and sellers often entertain cash offers. We review income, assets and credit at the outset, then stay involved with the lender, the appraiser and the escrow and title companies until funding. Where the file is ready, a jumbo loan may close in as little as 14 days.

Trusted by Homebuyers

More than 1,000 reviews from past clients tell a consistent story. LendFriend has helped thousands of homebuyers with responsive service, knowledgeable guidance, competitive financing and the experience to solve loans that other lenders may struggle with.

Loan Programs To Suit Every Santa Barbara County Borrower's Needs!

Through more than 40 wholesale lenders, LendFriend arranges jumbo loan options for buyers who need more flexibility than one bank can offer. Qualified Santa Barbara borrowers can choose among bank statement loans, asset depletion loans, and crypto mortgages.

Asset Depletion Loans in Santa Barbara

Asset Depletion Loans in Santa Barbara

An asset depletion mortgage allows eligible securities, retirement accounts and savings to be converted into qualifying income for a home purchase. It can be a strong fit for high-net-worth buyers and retirees in Montecito, Hope Ranch and Santa Ynez whose assets are substantial but whose reported income may be limited.

Learn More →

Self Employed Mortgages in Santa Barbara

Self Employed Mortgages in Santa Barbara

Business owners often show less taxable income on their returns than their operations generate. Our self-employed mortgage options can use bank statements to qualify without relying on tax-return income, giving winery owners, physicians and firm principals from Carpinteria to Solvang more ways to finance a home.

Learn More →

Crypto Mortgages in Santa Barbara

Crypto Mortgages in Santa Barbara

A crypto mortgage can allow qualified buyers to apply Bitcoin, Ethereum and other eligible digital assets toward qualifying for a home purchase without liquidating their holdings. Buyers throughout Santa Barbara, Montecito and Goleta may be able to finance up to $5 million with a jumbo crypto mortgage.

Learn More →

RSU Mortgages For Tech Employees in Santa Barbara

RSU Mortgages For Tech Employees in Santa Barbara

Restricted Stock Units can represent a significant portion of compensation for South Coast technology professionals. Our RSU mortgage program can use vested RSU income alongside salary, helping employees at companies such as Procore in Carpinteria, AppFolio and Deckers Brands in Goleta and Sonos in Santa Barbara qualify for higher loan amounts.

Learn More →

Buy Before You Sell in Santa Barbara

Buy Before You Sell in Santa Barbara

Our Buy Before You Sell program helps qualified homeowners purchase their next home before the current property sells. A bridge loan can free up equity from the departing residence for the down payment, so the new offer on a Montecito or Hope Ranch home can be made without a home-sale contingency and the existing property can be sold separately.

Learn More →

Jumbo No-Ratio Loans in Santa Barbara

Jumbo No-Ratio Loans in Santa Barbara

With a no-ratio loan, qualifying borrowers can obtain primary residence financing without a traditional debt-to-income calculation. These loans can be particularly useful for high-net-worth buyers and business owners in Santa Barbara and Montecito with substantial credit, assets and reserves who may not fit conventional income guidelines, and they are available for a primary residence only.
Learn More →

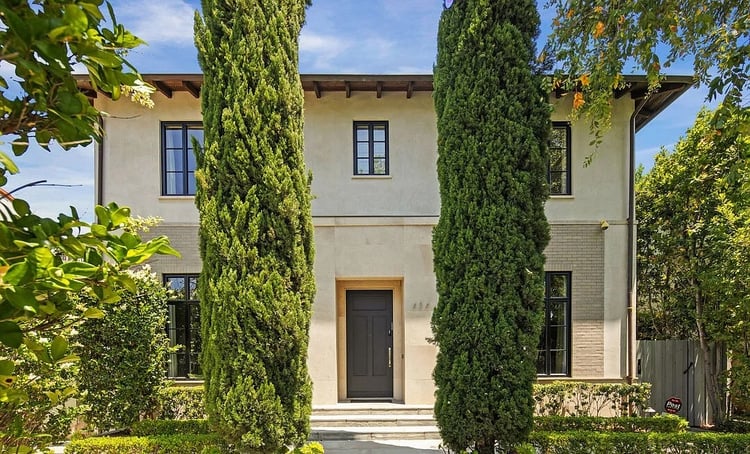
Luxury home near Santa Barbara, California

Straightforward Qualification That Works for Buyers in Montecito, Hope Ranch and Santa Ynez

Buyers in Santa Barbara, Montecito, Carpinteria and the Santa Ynez Valley want to know early what a jumbo lender will require. We review credit, income, assets, reserves and the property with you up front, so you make an offer with a program already identified.

Clear qualification guidelines for jumbo loans

We explain the credit score, debt-to-income, reserve and documentation standards each program carries before you commit to a property. The budget then rests on what a lender will approve.

More options for self-employed and retired buyers

LendFriend offers jumbo bank statement loans for eligible winery owners, practice owners and other self-employed buyers, and jumbo asset depletion loans for retirees and high-net-worth borrowers who qualify on eligible investment and retirement assets.

Get Started On Your Santa Barbara Jumbo Loan

Santa Barbara buyers bring us Montecito estates, Riviera homes with ocean views and ranch residences in the Santa Ynez Valley. LendFriend can help you find a home loan in California that reflects how you earn and hold your wealth.

Apply online or schedule a call, and our team will review your loan options, current jumbo mortgage rates in Santa Barbara County and the documents a lender will request. Qualified borrowers may also have the loan positioned for a quick close once escrow opens.

Home in the Santa Barbara & Santa Ynez Valley area of California

Jumbo Non-QM Loan Examples for Santa Barbara Buyers

Founders, executives, retirees and longtime owners in Santa Barbara County often arrive with a large loan request and a complicated financial picture. Each scenario below is an illustrative example. A lender might structure jumbo loans for California homes with asset depletion loans, bank statement loans and jumbo no-ratio loans for a purchase or a cash-out refinance. Lenders offer the jumbo no-ratio loan for a primary residence only.

$2.9M Asset Depletion Loan in Santa Barbara

A retired couple is buying a $4.5M home on the Riviera in Santa Barbara and prefers to keep a $9M portfolio invested. A jumbo asset depletion loan can treat brokerage and retirement balances as qualifying income for a $2.9M mortgage. The couple puts $1.6M down, about 36%, and sells no securities.

$4.2M Cash-Out Asset Depletion Loan in Carpinteria

A Carpinteria owner holds a beachfront home worth about $7.5M with a $1.5M mortgage and wants to fund a family office investment. A jumbo asset depletion loan can qualify a $4.2M cash-out refinance on a $15M portfolio, with no employment income documented. The new loan equals 56% of value and returns about $2.7M to the owner before closing costs.

$3.6M Bank Statement Loan in Santa Ynez

The owner of a Santa Ynez Valley hospitality business is buying a $5.2M home with acreage in Santa Ynez and shows limited taxable income. A jumbo bank statement loan can qualify a $3.6M mortgage on 24 months of business deposits in place of tax returns. With $1.6M down, about 31%, the loan can be ready inside a 30-day escrow.

$2M No-Ratio Loan in Goleta

A founder who sold his software company is buying a $3.4M primary residence in Goleta and has no salary to document. A jumbo no-ratio loan, available for a primary residence only, can provide a $2M mortgage based on equity, credit and mortgage history. He puts $1.4M down, about 41%, and the lender calculates no debt-to-income ratio.

Jumbo Mortgage Options Beyond Santa Barbara

Santa Barbara buyers rarely limit their real estate to one county. Some are moving for work, some are adding a second home, and others keep a residence in a larger city. Our jumbo financing reaches most of the markets on their lists.

In California, we finance higher-priced homes from Montecito and the Santa Ynez Valley to the Central Coast, the Monterey Peninsula, and Lake Tahoe. Our jumbo loans in California cover luxury primary residences, second homes, and investment properties across the state.

Many owners here also keep a home to the south. Just down the 101, Ventura County communities such as Ojai, Westlake Village and the Ventura coast draw Santa Barbara buyers who want more land or a shorter drive to work. We arrange jumbo loans in Los Angeles for buyers in Malibu, Pacific Palisades, Brentwood, and Beverly Hills, and in the San Fernando Valley for Calabasas, Hidden Hills and Encino. Others look to Orange County communities such as Newport Beach and Laguna Beach, or to San Diego neighborhoods including La Jolla and Del Mar. Buyers with ties to Silicon Valley often purchase in the Bay Area.

Second homes take Santa Barbara owners to the mountains as well. We work with buyers in Idaho resort markets such as Sun Valley and in Colorado ski towns including Aspen and Telluride. Other clients are relocating to Texas, where Austin and Dallas attract business owners and executives.

Whether your next purchase is in Santa Barbara County, elsewhere in California, or in another state, we can help you compare jumbo mortgage options before you make an offer.

BORROWER TESTIMONIALS

See Why Jumbo Borrowers Choose LendFriend Mortgage

See how homebuyers across the country have worked with LendFriend Mortgage to navigate larger loan amounts, complex income, and jumbo mortgage financing.

FAQs – Getting a Jumbo Loan In Santa Barbara

What loan amount qualifies as a jumbo loan in Santa Barbara County?

In Santa Barbara County, the 2026 conforming loan limit for a one-unit property is $941,850. Any mortgage above this figure is a jumbo loan.

The 2026 limits for Santa Barbara County, which apply from Carpinteria and Goleta to Solvang and Santa Ynez, are:

  • Single-unit property: $941,850

  • Two-unit property: $1,205,750

  • Three-unit property: $1,457,450

  • Four-unit property: $1,811,300

Homes in Montecito, Hope Ranch, the Riviera, and the Santa Ynez Valley regularly exceed these thresholds, so jumbo mortgages are the standard way to finance a purchase here.

How much can I borrow with a jumbo loan in Santa Barbara?

Borrowers with strong qualifications can obtain jumbo loans in California well into the multi-million range. Credit score, loan-to-value ratio, and reserves set the amount a lender will approve. Higher credit scores and larger reserves usually bring lower jumbo rates and better terms. Jumbo bank statement loans reach $7M for eligible self-employed buyers.

Do jumbo loans require perfect credit?

No. A score of 750 or above earns the best jumbo pricing. A borrower with a lower score may still qualify by showing compensating strengths, such as a larger down payment or substantial liquid assets.

Can I get a jumbo loan in Santa Barbara if I am self-employed or have complex income?

Yes. Santa Barbara borrowers can use Jumbo Non-QM programs, including bank statement loans and asset depletion loans. Business owners, consultants, and retirees buying in Montecito or the Santa Ynez Valley may qualify without W-2s or traditional tax returns. The choice between an asset depletion loan and a bank statement loan depends on whether business deposits or investment balances are the stronger basis for qualification.

What property types are eligible for jumbo financing in Santa Barbara?

In Santa Barbara County, single-family homes, condos, townhomes, and 2–4 unit properties are all eligible. We arrange jumbo financing for a Montecito estate, a Mesa home near the bluffs, a downtown Santa Barbara condo, or a home on acreage in Santa Ynez. Properties with large acreage or agricultural use may face additional lender review, and we confirm eligibility before you write an offer.


How do jumbo loan interest rates compare to conventional rates?

Jumbo rates in Santa Barbara County are often competitive with conventional rates and can be lower. Lenders compete for well-qualified jumbo borrowers in established markets such as Montecito and Hope Ranch.

Is an adjustable-rate mortgage a good option for a jumbo loan in Santa Barbara?

It may be, and the length of time you plan to own the home decides it. With a 5/1 or 7/1 jumbo ARM, the rate is fixed for the first five or seven years and often starts below a 30-year fixed. On a Montecito or Riviera purchase, the lower initial payment is one reason ARMs have returned for jumbo borrowers. Buyers who expect to refinance or relocate are the usual fit. A buyer with a shorter horizon should weigh how an ARM performs when a sale is planned within a few years.

How much equity can I access with a jumbo cash-out refinance in Santa Barbara?

Lenders examine credit, reserves, and the appraisal. The maximum loan-to-value is commonly near 80% on a primary home and lower on very large loans. Owners in Montecito, San Roque, and Goleta can draw on their equity through a jumbo cash-out refinance. The new jumbo loan pays off the existing mortgage and returns the difference in cash. Santa Barbara homeowners with VA entitlement may be able to borrow more of the home's value with a VA cash-out refinance or a VA jumbo cash-out refinance. Neither VA loan carries monthly mortgage insurance, which lowers the payment.

Is a VA loan an option for a jumbo purchase in Santa Barbara?

Eligible veterans and active-duty service members, including those stationed at Vandenberg Space Force Base, may be able to use a VA loan above the conventional limit. Qualified borrowers may buy a higher-priced Santa Barbara County home with $0 down and no monthly PMI. Full entitlement may allow VA jumbo loans above the county limit with no set cap.

Can I refinance a jumbo loan in Santa Barbara?

Yes. A jumbo refinance can lower the rate, move an ARM into a fixed loan, or release equity from a high-value home. Owners of local companies have refinancing options for California business owners that rely on deposits for income.

What can I do if a bank denied my jumbo loan in Santa Barbara?

One bank's denial usually reflects that bank's internal overlays, not the borrower's ability to repay. Bonus income, RSUs, business income, and large asset balances are each treated differently by wholesale jumbo lenders. As a broker, we can take the same Santa Barbara file to a lender whose guidelines fit it. Buyers already in escrow still have options when a jumbo loan is denied.

How much do I need to put down on a jumbo loan in Santa Barbara?

Most jumbo lenders require 10% to 20% down on a primary residence in Santa Barbara County. The lowest down payments are reserved for borrowers with the strongest credit and reserves. Second homes and investment properties usually call for more. Lenders also look at reserves after closing, and down payments on jumbo Non-QM mortgages vary by program, occupancy, and loan size. Buyers should also budget for average closing costs in California.

Learn More About Jumbo Non-QM Loans

And our Learning Center gives you access to everything you need to know about jumbo loans, from down payment options and rate structure to underwriting, reserves, and refinancing. Read some of our favorite jumbo loan articles below.

The LendFriend Advantage for Jumbo Borrowers in California

LendFriend Mortgage treats jumbo lending as a primary discipline. Each borrower is matched with a jumbo lender that fits the property, the financial profile, and the objective. We charge no hidden fees and run the process to close quickly. Santa Barbara buyers can choose a 30-year fixed loan, a 7/1 ARM, or a flexible Non-QM option.

Around the Clock

Our team is available seven days a week to answer questions, review pricing and keep your loan moving. Whether you are buying in Santa Barbara, Montecito, Carpinteria, Solvang or elsewhere in Santa Barbara County, you can reach someone who knows your file and can give you a clear answer.

Loan Options

Access fixed-rate jumbo loans, ARMs, bank statement loans, asset depletion loans and other specialized mortgage programs through more than 40 wholesale lenders. Those relationships give us more flexibility to match the financing to your income, assets and property.

Get Pre-Approved Quickly

A strong pre-approval can make a meaningful difference when competing for a higher-priced home. We review your financial profile early, identify the right loan program and issue pre-approvals promptly so you can make an offer with confidence.

Personalized Mortgage Guidance

You work directly with an experienced mortgage professional who helps you understand your options, prepares the file for underwriting and remains involved through closing. Complex income, large asset portfolios and unusual property scenarios get the attention they require.

Close in as little as 14 days

Our lending relationships and experience with larger loan amounts help us move qualified jumbo borrowers through underwriting efficiently. In competitive markets like Santa Barbara, Goleta and Solvang, many loans can close in as little as 14 days when timing matters.

Contact us today to get a custom rate quote for your Santa Barbara home financing in less than 2 minutes.