Skip to content

Jumbo Non-QM Loans in the Inland Empire, California

Temecula, Murrieta, Chino Hills and Lake Arrowhead attract buyers purchasing wine country estates, gated golf community homes and lakefront properties across the Inland Empire. LendFriend offers jumbo Non-QM financing, including asset depletion loans for borrowers with substantial investment portfolios and bank statement loans for self-employed buyers, with more flexible qualification standards than many traditional banks provide.

Why Homebuyers Trust LendFriend With Their Jumbo Loans in the Inland Empire

The conforming limit in Riverside and San Bernardino counties sits well below the coastal counties, so a jumbo loan comes into play at a lower price point here. LendFriend works with buyers of primary residences, second homes and investment properties across both counties, placing loans through jumbo and jumbo Non-QM programs from more than 40 wholesale lenders.

We regularly help buyers finance homes in Temecula, Murrieta, Rancho Cucamonga, Chino Hills, Lake Arrowhead and Redlands, where estate lots, part-time use and business income can complicate a lender's review.

Jumbo Loans Built Around the Borrower

A salaried buyer with savings usually qualifies without much difficulty. A trucking company owner, a physician with a practice or a retiree living on a portfolio may show far less on a tax return than they can afford.

LendFriend offers jumbo loans for each of these borrowers, including:

  • Bank statement jumbo loans for eligible self-employed borrowers who document income with 12 or 24 months of business or personal deposits rather than tax returns
  • Asset depletion jumbo loans for eligible retirees and investors who qualify on brokerage and retirement account balances
  • No-ratio jumbo loans for eligible borrowers buying or refinancing a primary residence, with approval based on credit, equity and reserves instead of an income calculation

Financing for Wine Country Estates, Lake Homes and Golf Properties

Inland Empire purchases above the conforming limit tend to be larger properties. Buyers want acreage and a vineyard in the Temecula Valley or a lakefront home at Lake Arrowhead or Big Bear Lake. Others want a residence inside a gated golf community such as Bear Creek in Murrieta or Vellano in Chino Hills.

We help borrowers finance estate lots, lake and mountain second homes and properties with agricultural use. Acreage, well and septic systems, part-time occupancy and the source of the borrower's income all affect which lender fits, and we sort that out before an offer goes in.

A Faster, More Responsive Jumbo Process

Well-priced homes in Temecula and Chino Hills draw buyers from Orange County and San Diego, and sellers compare closing timelines along with price. We review income, assets and credit at the start and stay in contact with the lender, the appraiser and the escrow and title companies until the loan funds. A prepared borrower may close a jumbo loan in as little as 14 days.

Trusted by Homebuyers

We’ve helped thousands of buyers secure financing, with more than 1,000 reviews from clients who consistently mention our responsiveness, attention to detail and ability to handle complex mortgage scenarios without losing momentum.

Loan Programs To Suit Every Inland Empire Borrower's Needs!

Through relationships with more than 40 wholesale lenders, LendFriend arranges jumbo loan options for buyers who need more flexibility than a conventional lender gives. Inland Empire borrowers who qualify have access to bank statement loans, asset depletion loans, and crypto mortgages.

Asset Depletion Loans in the Inland Empire

Asset Depletion Loans in the Inland Empire

An asset depletion mortgage allows eligible brokerage accounts, retirement funds and savings to be converted into qualifying income for a home purchase. It can be a strong fit for retirees and high-net-worth buyers in Temecula, Lake Arrowhead and Canyon Lake whose assets are substantial but whose earned income may be limited.

Learn More →

Self Employed Mortgages in the Inland Empire

Self Employed Mortgages in the Inland Empire

Business owners across the Inland Empire often report less taxable income than their cash flow would suggest. Our self-employed mortgage options can use bank statements to qualify without relying on tax-return income, giving trucking and logistics operators, builders and franchise owners across Riverside and San Bernardino counties more ways to finance a home.

Learn More →

Crypto Mortgages in the Inland Empire

Crypto Mortgages in the Inland Empire

A crypto mortgage can allow qualified buyers to use Bitcoin, Ethereum and other eligible digital assets to help qualify for a home purchase without selling their holdings. Buyers throughout Temecula, Chino Hills and Big Bear Lake may be able to finance up to $5 million with a jumbo crypto mortgage.

Learn More →

RSU Mortgages For Corporate Employees in the Inland Empire

RSU Mortgages For Corporate Employees in the Inland Empire

Restricted Stock Units can represent a meaningful share of compensation for Inland Empire professionals, including residents who commute to Orange County and San Diego employers. Our RSU mortgage program can use vested RSU income alongside salary, helping employees at companies such as Monster Beverage in Corona, Abbott in Temecula and Amazon qualify for higher loan amounts.

Learn More →

Buy Before You Sell in the Inland Empire

Buy Before You Sell in the Inland Empire

Our Buy Before You Sell program helps qualified Inland Empire homeowners purchase their next home before the current property sells. A bridge loan can draw equity from the departing residence for the down payment, so the new offer can be made without a home-sale contingency and the existing home in Rancho Cucamonga or Corona can be sold separately.

Learn More →

Jumbo No-Ratio Loans in the Inland Empire

Jumbo No-Ratio Loans in the Inland Empire

With a no-ratio loan, qualifying borrowers can finance a primary residence without a traditional debt-to-income calculation. These loans can be particularly useful for high-net-worth buyers and business owners in Temecula and Chino Hills with substantial credit, equity and reserves who may not fit conventional income guidelines, and they are available for a primary residence only.
Learn More →

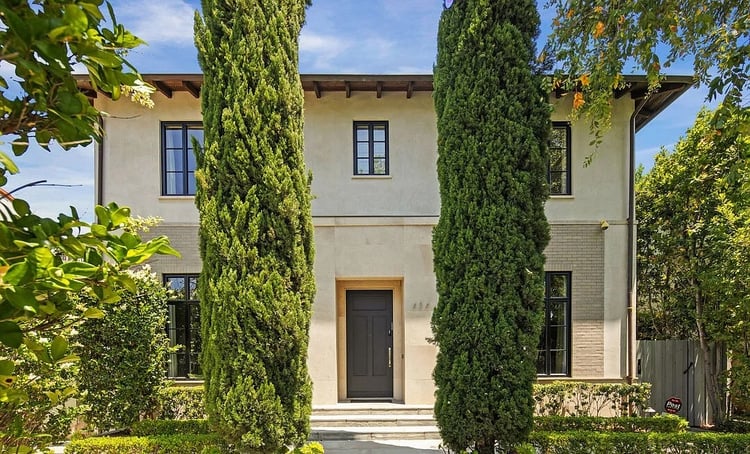
Luxury home near Temecula, California

Straightforward Qualification That Works for Buyers in Temecula, Rancho Cucamonga and Chino Hills

Before they tour homes, buyers in Temecula, Murrieta, Rancho Cucamonga and Chino Hills want to know what a jumbo lender will require. We go through credit, income, assets, reserves and the property with you first, so the programs you pursue are ones you can close.

Clear qualification guidelines for jumbo loans

Credit score, debt-to-income, reserve and documentation standards differ from one jumbo program to the next. We put the requirements in front of you at the start, so your price range rests on what a lender will approve.

More options for self-employed and retired buyers

LendFriend offers jumbo bank statement loans for eligible business owners and contractors who qualify on deposits, and jumbo asset depletion loans for retirees and high-net-worth buyers who qualify on eligible investment and retirement accounts.

Get Started On Your Inland Empire Jumbo Loan

A vineyard estate in Temecula, a lakefront home in Lake Arrowhead or a golf community residence in Chino Hills each calls for a lender that understands the property. LendFriend can help you find a home loan in California that matches your income, your assets and the home.

Apply online or schedule a call with our team to compare loan options, current jumbo mortgage rates in the Inland Empire and the documents your lender will request. Qualified borrowers may also be positioned for a short escrow once a seller accepts the offer.

Home in the Inland Empire area of California

Jumbo Non-QM Loan Examples for Inland Empire Buyers

Business owners, retirees and move-up buyers in Riverside and San Bernardino counties often need a loan above the conforming limit. Many also need a lender that will accept income outside a tax return. Each example below is illustrative and shows how a lender could structure jumbo loans for California homes through asset depletion loans, bank statement loans and jumbo no-ratio loans. The structures apply to a purchase or a cash-out refinance, and a jumbo no-ratio loan is offered for a primary residence only.

$1.8M Asset Depletion Loan in Lake Arrowhead

A semi-retired couple from Orange County is buying a $2.6M lakefront second home in Lake Arrowhead and holds $6.5M in brokerage and IRA accounts. A jumbo asset depletion loan can convert those balances into qualifying income for a $1.8M mortgage. The couple puts $800,000 down, or about 31%, and sells no investments.

$2.6M Cash-Out Asset Depletion Loan in Murrieta

A couple in La Cresta, near Murrieta, owns a home on acreage worth about $4.2M with a $900,000 mortgage and wants capital for a second property. A jumbo asset depletion loan can qualify a $2.6M cash-out refinance on a $10M investment portfolio, with no employment income in the file. The new loan equals 62% of value and returns about $1.7M to the owners before closing costs.

$2.4M Cash-Out Bank Statement Loan in Temecula

The owner of a trucking company holds a Temecula wine country estate worth about $3.6M with a $1.2M mortgage, and depreciation leaves little taxable income. A jumbo bank statement loan can qualify a $2.4M cash-out refinance on 12 months of business deposits, with no tax returns. The loan equals 67% of value and releases about $1.2M for equipment and expansion.

$1.7M No-Ratio Loan in Chino Hills

A physician couple is buying a $3M primary residence in the Vellano community of Chino Hills and would rather not document income from a new practice. A jumbo no-ratio loan, offered for a primary residence only, can provide a $1.7M mortgage on credit, equity and reserves. The buyers put $1.3M down, or about 43%, and the lender calculates no debt-to-income ratio.

Jumbo Mortgage Options Beyond the Inland Empire

Inland Empire buyers shop a wide area, and many compare homes in neighboring counties before they decide. Others are purchasing a second home or planning a move out of California. We arrange jumbo financing in many of the markets on their lists.

Throughout California, we finance higher-priced homes from Temecula and Chino Hills to the coast and the mountains. Our jumbo loans in California serve buyers of luxury primary residences, second homes, and investment properties in every region of the state.

Chino Hills and Corona buyers often look west to Orange County, including Yorba Linda, Anaheim Hills, and Irvine. Temecula and Murrieta sit close to north San Diego County, and many buyers consider both sides of the county line. Families in Rancho Cucamonga and Upland follow the 210 corridor west and compare the foothills with Pasadena and the San Gabriel Valley. Others move toward Los Angeles for work or follow technology careers to the Bay Area.

For buyers leaving the state, we arrange jumbo loans in Idaho, Texas, and Tennessee, three states that draw many relocating Californians. Second-home buyers also look to Colorado mountain towns.

We can help you compare jumbo mortgage options before you make an offer, whether the property is in the Inland Empire, on the coast, or in another state.

BORROWER TESTIMONIALS

See Why Jumbo Borrowers Choose LendFriend Mortgage

See how homebuyers across the country have worked with LendFriend Mortgage to navigate larger loan amounts, complex income, and jumbo mortgage financing.

FAQs – Getting a Jumbo Loan In the Inland Empire

What loan amount qualifies as a jumbo loan in Riverside County and the Inland Empire?

Riverside County has a 2026 conforming loan limit of $832,750 for a one-unit property. Mortgages above this amount in either county are jumbo loans.

San Bernardino County shares the same 2026 limits, which are:

  • Single-unit property: $832,750

  • Two-unit property: $1,066,250

  • Three-unit property: $1,288,800

  • Four-unit property: $1,601,750

These limits are well below those of Los Angeles and Orange counties. Homes in Temecula, Chino Hills, Rancho Cucamonga, and Lake Arrowhead regularly exceed them. Many Inland Empire buyers therefore need a jumbo mortgage at a lower price point than coastal buyers do.

How much can I borrow with a jumbo loan in the Inland Empire?

Jumbo loan amounts start just above the conforming limit and extend to several million dollars for qualified borrowers. Most jumbo loans in California are sized by credit score, loan-to-value ratio, and reserves. Applicants with excellent credit and large reserves generally receive the most competitive rates and terms.

Do jumbo loans require perfect credit?

No. Borrowers at 750 and above receive the most favorable jumbo pricing, and a lower credit score raises the mortgage rate. Approval remains possible below that level when the borrower adds a larger down payment or shows significant liquid assets.

Can I get a jumbo loan in the Inland Empire if I am self-employed or have complex income?

Yes. Jumbo Non-QM programs are built for these borrowers, and the main ones are bank statement loans and asset depletion loans. Business owners, investors, and retirees buying in Temecula or Rancho Cucamonga may qualify without providing W-2s or traditional tax returns. A jumbo bank statement loan can reach $7M, with income drawn from 12 or 24 months of deposits. Borrowers turned away over paperwork have other alternatives for California jumbo loans as well.

What property types are eligible for jumbo financing in the Inland Empire?

Jumbo financing applies to single-family homes, townhomes, condos, and properties of two to four units. We finance a Temecula vineyard estate, a Canyon Lake waterfront home, a Big Bear Lake cabin near the ski resorts, or a Riverside home in Hawarden Hills. Mountain and lake homes are frequently bought for part-time use, and lenders price a second home and an investment property differently.


How do jumbo loan interest rates compare to conventional rates in the Inland Empire?

Inland Empire jumbo rates often track close to conforming loan rates, and a strong file can price below them. Lenders compete for well-qualified borrowers in markets such as Temecula and Chino Hills.

Is an adjustable-rate mortgage a good option for a jumbo loan in the Inland Empire?

A jumbo ARM may fit if you expect to sell or refinance within the fixed period. The 5/1 and 7/1 versions hold the rate for five or seven years and generally start lower than a 30-year fixed loan. Lower early payments on a Temecula or Rancho Cucamonga purchase help explain the renewed use of ARMs among jumbo borrowers. Move-up buyers and executives who relocate are frequent users. A planned sale changes the calculation, so buyers should weigh how an adjustable-rate mortgage fits a short ownership period.

How much equity can I access with a jumbo cash-out refinance in the Inland Empire?

Equity in Temecula, Corona, and Redlands homes can be released through a jumbo cash-out refinance. A larger jumbo loan replaces the existing mortgage, and the owner takes the difference in cash. The usual ceiling is around 80% of value on a primary home, lower for very large loans, and it depends on credit, reserves, and the appraisal. Veterans and service members with VA entitlement may qualify for more through a VA cash-out refinance or a VA jumbo cash-out refinance. Either VA loan comes without monthly mortgage insurance.

Can veterans finance a higher-priced home in the Inland Empire with a VA loan?

Eligible veterans and active-duty service members, including those serving at March Air Reserve Base and Marine Corps Base Camp Pendleton, may be able to use a VA loan above the conventional limit. Qualified borrowers may finance a higher-priced home in Temecula, Murrieta, or Riverside with $0 down and no monthly PMI. Borrowers with full entitlement may find that VA jumbo loans carry no set loan limit.

Can I refinance a jumbo loan in the Inland Empire?

Yes. Reasons for a jumbo refinance include a lower rate, a switch from an adjustable to a fixed loan, and access to home equity. Self-employed owners can document income from deposits under the mortgage refinancing options for business owners available in California.

What can I do if a bank denied my jumbo loan in the Inland Empire?

A jumbo denial at a bank is often the product of that bank's overlays. Wholesale jumbo lenders vary in how they evaluate bonus income, RSUs, business income, and sizable asset balances. As a broker, we can move the same documents to a lender whose guidelines accommodate the borrower. A buyer with a contract deadline has several remedies once a jumbo loan has been denied.

How much do I need to put down on a jumbo loan in the Inland Empire?

Most jumbo lenders in Riverside and San Bernardino counties require 10% to 20% down on a primary residence. Strong credit and reserves are needed for the 10% options, and second homes in Lake Arrowhead or Big Bear Lake usually require a larger down payment. Lenders review the reserves that remain after closing. Program, occupancy, and loan size determine jumbo and Non-QM mortgage down payments. Buyers should also plan for escrow and title fees, which are part of average closing costs in California.

Learn More About Jumbo Non-QM Loans

And our Learning Center gives you access to everything you need to know about jumbo loans, from down payment options and rate structure to underwriting, reserves, and refinancing. Read some of our favorite jumbo loan articles below.

The LendFriend Advantage for Jumbo Borrowers in California

LendFriend Mortgage treats jumbo lending as a primary discipline. Each borrower is matched with a jumbo lender that fits the property, the financial profile, and the objective. We charge no hidden fees and run the process to close quickly. Inland Empire buyers can choose a 30-year fixed loan, a 7/1 ARM, or a flexible Non-QM option.

Around the Clock

Our team is available seven days a week to answer questions, review pricing and keep your loan moving. Whether you are buying in Temecula, Murrieta, Chino Hills or elsewhere in the Inland Empire, you can reach someone who knows your file and can give you a clear answer.

Loan Options

Access fixed-rate jumbo loans, ARMs, bank statement loans, asset depletion loans and other specialized mortgage programs through more than 40 wholesale lenders. This breadth gives us more flexibility to match the financing to your income, assets and property.

Get Pre-Approved Quickly

A strong pre-approval can make a meaningful difference when competing for a higher-priced home. We review your financial profile early, identify the right loan program and issue pre-approvals quickly so you can make an offer with confidence.

Personalized Mortgage Guidance

You work directly with an experienced mortgage professional who helps you understand your options, prepares the file for underwriting and stays involved through closing. Complex income, large asset portfolios and unusual property scenarios get the attention they require.

Close in as little as 14 days

Our lending relationships and experience with larger loan amounts help us move qualified jumbo borrowers through underwriting efficiently. In competitive markets like Temecula, Rancho Cucamonga and Chino Hills, many loans can close in as little as 14 days when timing matters.

Contact us today to get a custom rate quote for your Inland Empire home financing in less than 2 minutes.