<img height="1" width="1" style="display:none" src="https://www.facebook.com/tr?id=2297599040530378&amp;ev=PageView&amp;noscript=1">
Skip to content

Access The Equity In Your Florida Home With a Cash-Out Refinance

Rising home values across Florida have helped homeowners build substantial equity. A Florida cash-out refinance lets you access that equity for renovations, debt consolidation, investments, or other expenses. LendFriend helps you secure competitive rates and flexible financing options.

What Does a Cash-Out Refinance Mean for Florida Homeowners?

A cash-out refinance allows Florida homeowners to access their home equity by replacing their existing mortgage with a new, larger loan. The difference is paid to you in cash at closing after your current mortgage and closing costs are covered. Homeowners who own their property outright can also use a cash-out refinance to access equity.

Rising property values across Florida have helped homeowners accumulate substantial equity, particularly in markets like Miami, Naples, Tampa, and Palm Beach. For longtime homeowners, retirees, and seasonal residents, a cash-out refinance can provide access to significant funds for renovations, debt consolidation, investments, or other financial priorities.

Florida homeowners can typically access more equity from a primary residence than from a second home or investment property. Your available equity, current mortgage rates, property taxes, and insurance costs all influence how much you can borrow and what your new monthly payment will be.

Florida home with equity for a cash-out refinance

Why Florida Homeowners Trust LendFriend With Their Cash-Out Refinance

LendFriend Mortgage helps Florida homeowners access their equity with competitive cash-out refinance rates, flexible loan options, and expert guidance throughout the process. Whether you're refinancing a primary residence in Miami, a vacation home in Naples, or an investment property in Tampa, our team has the experience and lender relationships to help you secure financing that meets your goals.

From conventional cash-out refinances to jumbo and Non-QM programs, LendFriend offers financing options for homeowners with a wide range of financial profiles. We specialize in helping retirees, business owners, and high-net-worth borrowers access substantial equity, even when their income or assets fall outside traditional lending guidelines.


Cash-Out Refinance Options Beyond the Conventional Loan

The conventional cash-out refinance is widely used in Florida, yet it does not fit every owner. Retirees, second-home owners, veterans, and investors often have better choices:

  • Asset depletion loans allow eligible retirees and high-net-worth borrowers to turn brokerage and retirement balances into qualifying income while leaving their portfolios invested.
  • Bank statement loans allow eligible entrepreneurs and self-employed owners to qualify on deposits rather than solely on tax returns.
  • Jumbo cash-out refinances allow eligible owners of waterfront and luxury properties to borrow above the loan amounts conventional programs offer.
  • VA cash-out refinances and VA jumbo cash-out refinances allow eligible veterans and service members to take cash out of a primary residence.
  • DSCR loans can help investors refinance a long-term or vacation rental and take cash out based on the property's income.

Florida is where these programs are most useful. A retiree in Naples living on investments, a business owner in Tampa, or a seasonal resident with a paid-off home in Palm Beach may have substantial wealth that traditional income documentation fails to show.

Competitive Florida Cash-Out Refinance Rates and Fast Closings

LendFriend works with more than 40 wholesale lenders to help Florida homeowners secure competitive cash-out refinance rates, low lender fees, and favorable loan terms. Whether you're refinancing a primary residence, second home, or investment property, our extensive lender relationships help us deliver financing suited to your needs.

When timing matters, LendFriend moves quickly. We offer same-day preapprovals and can close many cash-out refinances in as little as 14 days, helping Florida homeowners access their equity without unnecessary delays.

Estimate how much cash you could borrow.

Email Icons (3)

Determine your home equity.

Say your Florida home is valued at $900,000 and you owe $350,000.

$900,000 – $350,000 = $550,000

Your equity is $550,000.

Calculator (1)

Calculate your maximum loan amount.

On a primary residence, lenders commonly allow a loan-to-value ratio (LTV) of 80%. Second homes and rentals are usually capped lower.

$900,000 × 80% LTV = $720,000

In this case the maximum refinance loan amount works out to $720,000.

Home loan

Estimate the cash you could borrow.

Take the new loan amount and subtract your current balance. Closing costs and Florida mortgage taxes come out of the remainder.

$720,000 – $350,000 = $370,000

As much as $370,000 may be available.

Need help structuring your Florida cash-out refinance?

Tell a loan specialist which property you want to borrow against and why. We will lay out the cash available, the payment, and the costs for each option.

Strategic Uses for Cash-Out Funds in Florida

Florida owners face costs that owners in other states rarely see, and they have opportunities to match. Their cash-out plans reflect both.

Popular Uses for Cash-Out Funds:

Storm Hardening and Renovations

A new roof, impact windows, and shutters protect the home and may reduce insurance premiums. Many owners combine those upgrades with a kitchen or pool project in one refinance.

Condo Special Assessments

Associations across the state are funding reserves and structural repairs, and the bills to unit owners can be large. Borrowing against the unit or another property spreads the cost over time.

Supplementing Retirement Income

Owners who are house-rich and prefer not to sell investments may draw on equity for living expenses. Cash-out refinancing for retirees often relies on assets instead of a paycheck to qualify.

Buying a Second Home or Rental

Equity in a primary residence frequently funds a vacation property or a rental. Investors who own rentals already may refinance them with a Florida DSCR loan, which is underwritten on the property's rent.

Business Investment

Florida has one of the highest rates of new business formation in the country. Owners use home equity for inventory, real estate, and expansion, and the refinancing options for Florida business owners include loans that do not require tax returns.

Paying Off Costly Debt

Card balances and personal loans carry rates far above a mortgage. Consolidating them may free up monthly cash flow.

Whatever the purpose, the benefit should exceed the cost of the added mortgage debt. We run that comparison with you.

Costs and Benefits Analysis

Expect closing costs of about 2% to 5% of the loan amount. Florida charges documentary stamp tax and intangible tax on a new mortgage, which most other states do not, along with the usual appraisal, title, and lender fees.

Next comes the rate. Owners who are replacing an older low-rate loan should count the extra interest on the existing balance and review other refinance options before deciding.

Budget for the full payment, including homeowners insurance, flood coverage where required, and property taxes. A refinance leaves the Florida homestead exemption on a primary residence in place because ownership does not change.

Cash-Out Refinance Programs for Florida Homeowners

LendFriend offers a wide range of Florida cash-out refinance options for primary residences, second homes, and investment properties. Our programs include conventional, jumbo, and Non-QM loans designed to meet the needs of homeowners with different financial profiles, including retirees, business owners, and real estate investors.

Conventional Cash-Out Refinances in Florida

Conventional Cash-Out Refinances in Florida

Conventional financing works for Florida primary homes, second homes, and rentals when income is fully documented. Loan-to-value limits are highest on a primary residence.

Learn More

Jumbo Cash-Out Refinances in Florida

Jumbo Cash-Out Refinances in Florida

Waterfront and luxury homes across Florida frequently call for jumbo loan amounts. Lenders weigh credit history, liquid reserves, and the equity that remains.

Learn More

Bank Statement Loans in Florida

Bank Statement Loans in Florida

Florida entrepreneurs can use bank statements to qualify for a cash-out refinance. Income is calculated from 12 or 24 months of deposits rather than tax returns.

Learn More

VA Cash-Out Refinances in Florida

VA Cash-Out Refinances in Florida

Florida veterans and service members may use a VA loan to take cash out of a primary residence. Monthly mortgage insurance does not apply.

Learn More

Asset Depletion Mortgages in Florida

Asset Depletion Mortgages in Florida

Florida retirees may qualify using savings, brokerage, and retirement accounts in place of employment income. Investments stay where they are.

Learn More

Crypto Mortgages in Florida

Crypto Mortgages in Florida

Florida founders and investors may qualify with eligible cryptocurrency and keep their positions. Digital assets are reviewed as part of the overall profile.

Learn More

DSCR Loans in Florida

DSCR Loans in Florida

Florida investors may take cash out of long-term and vacation rentals based on rental income. No personal income documents are required.

Learn More

No-Ratio Loans in Florida

No-Ratio Loans in Florida

On a Florida primary residence, a no-ratio loan removes the debt-to-income test. Equity, credit, and reserves take its place.
Learn More

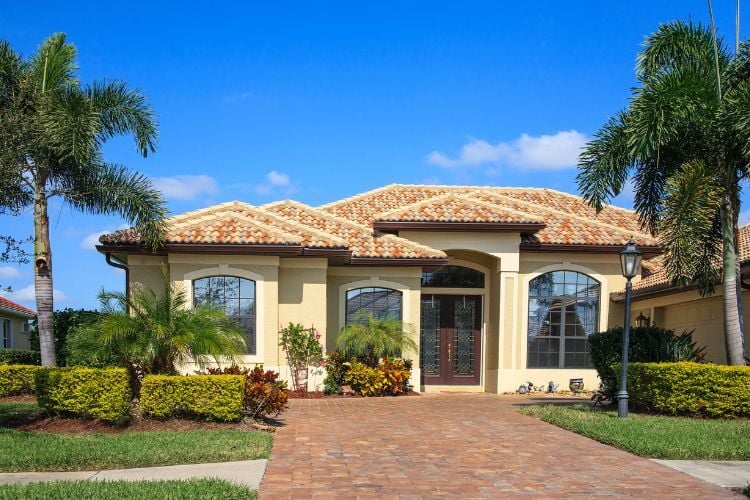
Florida home with a tile roof and palm trees

When a Florida Cash-Out Refinance Makes Sense

Rising property values across Florida have helped homeowners build substantial equity, particularly in markets like Miami, Naples, Tampa, and Palm Beach. Homeowners with significant equity may be able to access substantial cash while retaining a considerable ownership stake in their property.

For higher-value homes, a jumbo cash-out refinance may provide access to larger loan amounts, subject to lender requirements for credit, assets, and property value. Homeowners with more modest financing needs may qualify for conventional, FHA, or VA cash-out refinancing through our Florida home loan programs.

Ideal Conditions for Cash-Out Refinancing:

  • Substantial home equity or a low existing mortgage balance
  • Current mortgage rates that support your financial goals
  • Sufficient income or assets to qualify
  • A clear purpose for accessing your equity
  • A monthly payment that comfortably accounts for property taxes and insurance

Homeowners who meet these conditions are generally well positioned to explore competitive Florida cash-out refinance rates and financing options. LendFriend can help determine how much equity you can access and which programs best fit your financial situation.

Florida Cash-Out Refinance Requirements

Qualifying for a Florida cash-out refinance depends on your credit, income, available equity, and property type. Single-family homes generally have fewer requirements, while condos may require additional reviews of the association's finances, insurance coverage, and overall eligibility.

Conventional programs may accept credit scores starting at 620, while many Non-QM programs require at least 660. Higher credit scores generally qualify for more competitive rates, with the best pricing often available above 780. Retirees and investors may qualify through asset depletion loans in Florida using eligible investments and retirement savings, while business owners can use bank statement loans in Florida to qualify based on deposits.

Most cash-out refinances close within 30 to 45 days, although LendFriend can close qualifying loans in as little as 14 days. Insurance requirements and condo documentation are common causes of delays, so we address them early.

Key Qualification Factors:

  • Credit score of 620 for conventional loans or 660 for many Non-QM programs, with better pricing for stronger credit
  • Debt-to-income ratio generally below 50%
  • Sufficient home equity based on loan program and occupancy type
  • Verified income, business deposits, or eligible liquid assets
  • Acceptable homeowners and flood insurance coverage

LendFriend reviews your financial qualifications and property requirements upfront to identify potential issues, minimize delays, and help secure favorable loan terms.

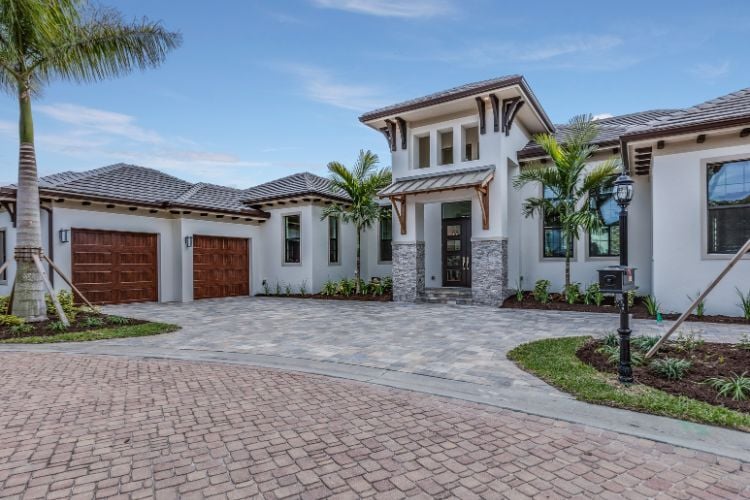
Florida home refinanced with a jumbo cash-out loan

How Florida Homeowners Use a Cash-Out Refinance

Here are examples of the cash-out refinances we arrange for Florida homeowners. Details are illustrative.

Gulf Breeze Homeowner Takes $1M Out to Diversify

A homeowner in Gulf Breeze wanted a $2.5M cash-out refinance on a high-value home, with $1M out for liquidity and investment flexibility. Tax returns alone did not support the new payment. We qualified the borrower with an asset depletion loan, and the proceeds were reinvested in the stock market.

Tampa Business Owner Buys a Warehouse With Home Equity

A business owner in Tampa owed $700,000 on a $1.7M home and needed about $500,000 to buy a warehouse for the company. Deductions on the business returns hid much of the real income. We used a bank statement loan based on 12 months of deposits and closed a $1.2M mortgage.

Palm Beach Second Home Covers an Assessment and a Renovation

A seasonal resident owed $800,000 on a $2.5M second home in Palm Beach and needed funds for a condo special assessment and renovations. The first lender would not take cash out of a second home at that loan size. We closed a $1.5M jumbo cash-out refinance that provided roughly $700,000.

Fort Lauderdale Investor Uses One Rental to Buy the Next

An investor owed $450,000 on a $1.2M vacation rental in Fort Lauderdale and wanted equity for a second property. Personal income was already committed to other mortgages. We closed an $800,000 DSCR loan that qualified on the rental income and provided about $350,000.

BORROWER TESTIMONIALS

What Homeowners Say About Their Cash-Out Refinance With LendFriend Mortgage

See what homeowners say about taking cash out of their home equity with LendFriend Mortgage, including refinances closed on a tight timeline.

Florida Cash-Out Refinance FAQs

How does a cash-out refinance work in Florida?

You replace your mortgage with a larger one and receive the difference at closing. A Florida cash-out refinance also includes state mortgage taxes in the closing costs.

Can I get a cash-out refinance on a Florida home with no mortgage?

Yes. A cash-out refinance on a paid-off home works the same way as any other, except that nearly the entire loan comes to you in cash after closing costs. Many Florida retirees use it to fund a purchase, help family, or add liquidity without selling investments.

Can I take cash out of a second home or vacation property in Florida?

Yes. A cash-out refinance on a second home is available in Florida, usually at a lower maximum loan-to-value ratio than a primary residence. Owners use the proceeds for improvements or for another purchase.

Can Florida veterans use a VA loan to access home equity?

Yes. Eligible veterans and service members may refinance a primary residence through the VA program and take cash out, often with more flexible terms than a conventional loan. Florida's large retired military community uses the program widely, and the pros and cons of a VA cash-out refinance are worth weighing against other options.

Is a HELOC or a cash-out refinance the better choice?

It depends on your current mortgage. Owners with a low existing rate often favor a HELOC, and owners with no mortgage or a high rate often favor refinancing. The HELOC versus cash-out refinance decision also turns on how much cash you need.

How can a mortgage broker help with a Florida cash-out refinance?

A broker has access to many lenders, which matters for condos, second homes, and retirement income. Mortgage brokers make cash-out refinances simpler by matching the file to the right lender at the start.

Can I use a cash-out refinance to pay a condo special assessment?

Yes. Proceeds can be used for any purpose, including a special assessment, and you can borrow against the unit itself or another property you own. The building still has to meet lender requirements, and the difference between warrantable and non-warrantable condos often decides which loan programs are available.

Does homeowners insurance affect my Florida cash-out refinance?

Yes. Lenders require adequate coverage, and the premium counts toward your qualifying payment, so a higher premium may reduce the loan amount. Choosing the right homeowners insurance policy before you apply can help on both fronts.

What credit score do I need for a cash-out refinance in Florida?

The minimum is 620 for a conventional cash-out refinance and 660 for the Non-QM programs many Florida retirees, business owners, and investors use. You will want a score above 700 to access better rates, and a 780 score earns the best rate. Because of how your credit score impacts your mortgage rate, even a modest improvement before you apply can lower the cost of the entire loan.

Learn More About Cash Out Refinances

Explore our Learning Center for expert guidance on Florida cash-out refinance rates, home equity requirements, loan options, and closing costs. Our resources help Florida homeowners understand their financing options and make informed decisions before refinancing.

Contact us today to start your Florida Cash-Out Refinance.

3-Sep-02-2024-03-11-26-3988-PM

Stronger Negotiating Position when Buying a Home 

The equity in your current home is unlocked and used as a downpayment on your new home; meaning no sales contingency required! Sellers HATE sales contingencies. Without a sales contingency, your offer is stronger, increasing your chances of buying your next home with ease.

4-3

Get the Highest and Best Sale Price

Without feeling pressured to sell quickly, you can wait for the best offer on your current home. List your home at the best time, market it effectively, and attract more competitive offers. With no rush, you can negotiate better terms and get the highest selling price.

1-1

Reduced Stress

Don't worry about finding temporary housing or organizing multiple moves. Avoid the chaos of having to coordinate the sale of your current home and the purchase of a new one. Transition seamlessly from one home to another and reduce stress or anxiety, making the moving process more manageable and organized.

2-4

Time for Improvements

Make necessary renovations or updates to your new property before you move in. Painting, remodeling, or other improvements would be more challenging if you were already living there. Moving into a freshly updated home (instead of living in it during renovations) is just so much nicer!