Skip to content

Jumbo Non-QM Loans in Napa and Sonoma, California

Napa and Sonoma draw buyers looking for vineyard-view estates, second homes and properties on acreage within reach of San Francisco. LendFriend offers jumbo Non-QM financing for borrowers who need added flexibility in how income, assets or the property are reviewed.

Why Homebuyers Trust LendFriend With Their Jumbo Loans in Napa and Sonoma

High-value homes in Napa and Sonoma counties often need financing that a standard jumbo mortgage does not provide. LendFriend works with buyers of primary residences, weekend homes and investment properties, and our jumbo and jumbo Non-QM programs come from more than 40 wholesale lenders.

We regularly help buyers finance homes in Napa, St. Helena, Calistoga, Healdsburg, Sonoma and Glen Ellen, where acreage, second-home use and self-employed income can complicate lender guidelines.

Jumbo Loans Built Around the Borrower

Wine country buyers earn and hold wealth in different ways. Some have salary income and large reserves, and others depend on a winery, a restaurant, a professional practice, company stock or retirement accounts.

LendFriend offers jumbo financing for these borrowers, including:

  • Bank statement jumbo loans for eligible self-employed borrowers who use 12 or 24 months of business or personal deposits to document income
  • Asset depletion jumbo loans for eligible borrowers whose investment and retirement assets support the loan
  • No-ratio jumbo loans for eligible borrowers who are financing a primary residence and want approval based mainly on credit, equity and reserves

Financing for Wine Country Estates, Second Homes and Acreage

Many Napa and Sonoma purchases are second homes used on weekends and through harvest season. Others are full-time residences for retirees and for owners who work in the wine and hospitality trades.

We help borrowers finance estates, homes on acreage and properties with a small hobby vineyard. Lenders look closely at occupancy, reserves, land use and homeowners insurance, and we address each item early in the process.

A Faster, More Responsive Jumbo Process

Estate properties in St. Helena, Healdsburg and Glen Ellen reach the market in small numbers, and a financed buyer often competes with cash. We collect income, asset and credit documents up front and work closely with the lender, the appraiser and the escrow and title companies. A prepared borrower may be able to close a jumbo loan in as little as 14 days.

Trusted by Homebuyers

We’ve financed homes for thousands of buyers across the country, and more than 1,000 reviews reflect the level of service behind those closings. Clients repeatedly mention our responsiveness, expertise, competitive pricing and ability to make complex loans feel manageable.

Loan Programs To Suit Every Napa and Sonoma County Borrower's Needs!

Our access to more than 40 wholesale lenders lets us arrange a jumbo loan for buyers whose finances do not fit a single bank's guidelines. Qualified Napa and Sonoma borrowers can choose among bank statement loans, asset depletion loans, crypto mortgages, and the other programs below.

Asset Depletion Loans in Napa and Sonoma

Asset Depletion Loans in Napa and Sonoma

An asset depletion mortgage may let you qualify for a home on your investment balances instead of employment income. Eligible assets include brokerage accounts, retirement funds, and savings. The loan suits retirees and high-net-worth buyers in St. Helena, Yountville, and Healdsburg who no longer draw a salary.

Learn More →

Self Employed Mortgages in Napa and Sonoma

Self Employed Mortgages in Napa and Sonoma

Winery owners, growers, restaurateurs, and consultants often report less taxable income than their businesses generate. We arrange self employed mortgage options that may qualify these borrowers on deposits, with no tax returns or W-2s. Business owners across Napa, Santa Rosa, Petaluma, and Sebastopol use these loans.

Learn More →

Crypto Mortgages in Napa and Sonoma

Crypto Mortgages in Napa and Sonoma

A crypto mortgage may allow a buyer to finance a wine country home without selling Bitcoin or Ethereum. Eligible borrowers qualify on their digital asset holdings, and no employment income is required. Long-term holders buying in Napa or Healdsburg can borrow up to $5M through a jumbo crypto mortgage.

Learn More →

RSU Mortgages For Tech Employees in Napa and Sonoma

RSU Mortgages For Tech Employees in Napa and Sonoma

Vested Restricted Stock Units may count as qualifying income, so you do not need to sell shares to qualify. Our RSU mortgage program serves equity-compensated professionals at Keysight Technologies and Medtronic in Santa Rosa. It also serves executives at Bay Area employers such as Salesforce and Nvidia who buy homes in wine country.

Learn More →

Buy Before You Sell in Napa and Sonoma

Buy Before You Sell in Napa and Sonoma

Our Buy Before You Sell program may let you purchase a Napa or Sonoma home before your current residence sells. We fund the purchase with a bridge loan secured by the home being sold. Eligible owners can use existing equity toward the down payment and submit an offer with no sale contingency. The sale of the departing home can then follow on its own schedule.

Learn More →

Jumbo No-Ratio Loans in Napa and Sonoma

Jumbo No-Ratio Loans in Napa and Sonoma

Purchase or refinance a primary residence above the conforming limit without a debt-to-income ratio. Approval for a no-ratio loan rests on credit, equity, reserves, and mortgage history. The structure may suit borrowers in Napa and Sonoma whose tax returns understate their means.
Learn More →

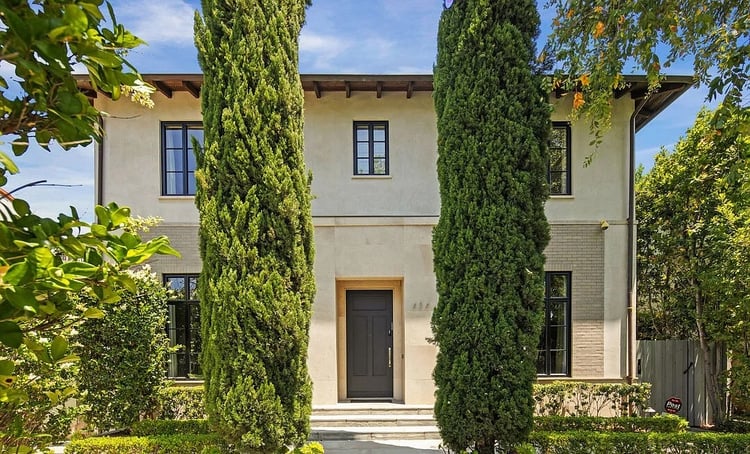
Luxury home near Napa, California

Straightforward Qualification That Works for Buyers in Napa, St. Helena and Healdsburg

Qualifying for a jumbo loan in Napa, St. Helena, Healdsburg or Sonoma starts with a full review. We examine credit, income, assets, reserves and the property first, and then tell you which programs fit before you write an offer.

Clear qualification guidelines for jumbo loans

Credit score, debt-to-income, reserve and documentation standards vary by lender and by occupancy. We explain them early so you have a realistic view of what you may qualify for on a primary residence or a second home.

More options for self-employed and retired buyers

LendFriend offers jumbo bank statement loans for eligible vintners, restaurateurs and other self-employed borrowers, and jumbo asset depletion loans for retirees and high-net-worth buyers qualifying with eligible investment and retirement assets.

Get Started On Your Napa and Sonoma Jumbo Loan

Your purchase may be an estate in St. Helena, a home near the Healdsburg Plaza or a Sonoma Valley property in Glen Ellen. LendFriend can help you find a home loan in California that matches how you earn and hold your wealth.

Apply online or schedule a call with our team to go through loan options, current jumbo mortgage rates and the paperwork a lender requires. Qualified borrowers can also ask us to structure the loan for a shorter escrow.

Home in the Napa & Sonoma Wine Country area of California

Jumbo Non-QM Loan Examples for Napa and Sonoma Buyers

Vintners, founders, retirees and second-home buyers in wine country often combine a large loan amount with income that is difficult to document. The examples in this section are illustrative and show how lenders can structure jumbo loans for California homes using asset depletion loans, bank statement loans and jumbo no-ratio loans. Jumbo no-ratio loans can be used for a primary residence only.

$3.2M Asset Depletion Loan in St. Helena

A retired couple buying a $5M home in St. Helena prefers to leave a $13M investment portfolio intact. A jumbo asset depletion loan can count brokerage and retirement balances as qualifying income for a $3.2M mortgage. The buyers put $1.8M down, or 36%, and sell no securities.

$2.7M Cash-Out Asset Depletion Loan in Healdsburg

A retired executive owns a Healdsburg home worth about $4.5M with a $1M mortgage and wants funds for improvements to the property. A jumbo asset depletion loan can qualify a $2.7M cash-out refinance on a $10M portfolio, with no pension or salary documented. The loan equals 60% of value and returns about $1.7M before closing costs.

$2.2M Bank Statement Loan in Sonoma

A winery owner buying a $2.9M home near the Sonoma Plaza shows limited taxable income after 8 years of reinvesting in the business. A jumbo bank statement loan can qualify a $2.2M mortgage on 24 months of business deposits, with no tax returns reviewed. The purchase can proceed with $700,000 down, about 24%.

$2.5M Cash-Out No-Ratio Loan in Napa

A founder holds a primary residence near Silverado Resort in Napa worth about $4.5M with a $1M mortgage, and most of her net worth is private company stock. A jumbo no-ratio loan, available for a primary residence only, can support a $2.5M refinance based on credit, equity, reserves and mortgage history. The loan equals 56% of value and releases about $1.5M, with no debt-to-income ratio calculated.

Jumbo Mortgage Options Beyond Napa and Sonoma

Wine country buyers frequently own or plan to own a home in a second market. Some are moving from a city residence, and others split the year between Napa or Sonoma and another state. We arrange jumbo financing in many of the places these buyers consider.

In California, we finance higher-priced homes from Calistoga and Healdsburg to the coast and the southern counties. Our jumbo loans in California apply to luxury primary residences, second homes, and investment properties across the state.

Many Napa and Sonoma owners keep a primary home in San Francisco, Marin County, or Silicon Valley and use the wine country property on weekends. Others maintain a residence in Los Angeles, Orange County, or San Diego.

Outside California, we work with buyers who look north to Oregon, where the Willamette Valley and Bend draw wine country owners. Ski and summer homes lead others to Idaho markets such as Sun Valley and Coeur d'Alene and to Colorado resort towns such as Aspen and Telluride. Some relocate to Texas, where Austin and Dallas attract corporate moves.

Whether the next purchase is in Napa Valley, on the Sonoma coast, or in another state, we can help you compare jumbo mortgage options before you make an offer.

BORROWER TESTIMONIALS

See Why Jumbo Borrowers Choose LendFriend Mortgage

See how homebuyers across the country have worked with LendFriend Mortgage to navigate larger loan amounts, complex income, and jumbo mortgage financing.

FAQs – Getting a Jumbo Loan In Napa and Sonoma

What loan amount qualifies as a jumbo loan in Napa County and Sonoma County?

In Napa County, the 2026 conforming loan limit for a one-unit property is $1,017,750. A mortgage above this figure is a jumbo loan.

The 2026 limits for Napa County appear below. Sonoma County has a lower one-unit limit of $897,000, so a loan above $897,000 is a jumbo loan in Santa Rosa, Healdsburg, and Sonoma.

  • Single-unit property: $1,017,750

  • Two-unit property: $1,302,900

  • Three-unit property: $1,574,900

  • Four-unit property: $1,957,250

Homes in St. Helena, Napa, Healdsburg, and Sonoma regularly exceed these limits, and most purchases at these prices require a jumbo mortgage.

How much can I borrow with a jumbo loan in Napa or Sonoma?

Borrowers with strong files can obtain jumbo loans in California for several million dollars. The approved amount depends on credit score, loan-to-value ratio, and reserves. Jumbo bank statement loans reach $7M, and higher credit and larger reserves generally earn better pricing.

Do jumbo loans in Napa and Sonoma require perfect credit?

No. A credit score of 750 or above earns the most favorable jumbo pricing. A borrower with a lower score may still qualify by offsetting it with a larger down payment or significant liquid reserves.

Can I get a jumbo loan in Napa or Sonoma if I am self-employed or have complex income?

Yes. We arrange Jumbo Non-QM programs such as bank statement loans and asset depletion loans. Winery owners, consultants, and retirees buying in Healdsburg or St. Helena may qualify without W-2s or tax returns. The choice between asset depletion loans and bank statement loans depends on whether deposits or account balances better reflect the borrower's capacity.

What property types are eligible for jumbo financing in Napa and Sonoma?

Jumbo loans can finance single-family homes, condos, townhomes, and 2–4 unit properties. We arrange jumbo financing for a St. Helena estate, a Silverado Resort residence, a Healdsburg farmhouse, or a Glen Ellen home on acreage. A home with a small hobby vineyard may still qualify for residential financing, while a parcel operated as a commercial vineyard or winery generally requires agricultural or commercial lending. Buyers who plan to rent the home should confirm whether the lender will treat it as a second home or an investment property.


How do jumbo loan interest rates compare to conventional rates in Napa and Sonoma?

Jumbo rates in Napa and Sonoma counties are frequently in line with conventional rates and sometimes below them. Lenders price aggressively for well-qualified jumbo borrowers in established markets such as St. Helena and Healdsburg.

Is an adjustable-rate mortgage a good option for a jumbo loan in Napa or Sonoma?

It may be, and the answer depends on how long you expect to own the home. A 5/1 or 7/1 jumbo ARM fixes the rate for the first five or seven years and often prices below a 30-year fixed. The savings in the early years help explain why ARMs have come back for jumbo borrowers. Second-home buyers who expect to sell or refinance within a decade are common candidates. Each borrower should weigh how an ARM performs when a sale is planned before the fixed period ends.

How much equity can I access with a jumbo cash-out refinance in Napa or Sonoma?

Jumbo lenders commonly cap loan-to-value near 80% on a primary home and set lower caps on very large loans, after reviewing credit, reserves, and the appraisal. Owners in Napa, Sonoma, and Healdsburg can draw on their equity through a jumbo cash-out refinance. A larger jumbo loan pays off the existing mortgage, and the owner receives the remaining proceeds in cash. Wine country homeowners with VA entitlement may be able to borrow against more of the home's value with a VA cash-out refinance or a VA jumbo cash-out refinance. Both VA loans carry no monthly mortgage insurance.

Can veterans finance a higher-priced home in Napa and Sonoma with a VA loan?

Eligible veterans and active-duty service members may be able to use a VA loan above the conforming limit. Eligible borrowers include personnel stationed at Travis Air Force Base in Fairfield and Coast Guard Training Center Petaluma. Qualified borrowers may buy a higher-priced home with $0 down and no monthly PMI. A borrower with full entitlement may use VA jumbo loans without a set loan limit.

Can I refinance a jumbo loan in Napa or Sonoma?

Yes. A jumbo refinance can lower the rate, replace an ARM with a fixed loan, or draw equity from a high-value home. Vintners and other self-employed owners can also use the refinancing options for California business owners, which qualify income from deposits.

What can I do if a bank denied my jumbo loan in Napa or Sonoma?

One bank's denial usually reflects its own overlays, not a borrower's ability to qualify elsewhere. Wholesale jumbo lenders differ in how they count bonus income, RSUs, business income, and large asset balances. As a broker, we can place the same file with a lender whose guidelines fit it. Buyers already in escrow still have several paths forward when a jumbo loan is denied.

How much do I need to put down on a jumbo loan in Napa or Sonoma?

Jumbo lenders generally require 10% to 20% down on a primary residence in Napa and Sonoma counties. The 10% options are reserved for borrowers with the strongest credit and reserves. Second homes and investment properties, which are common in wine country, usually call for a larger down payment. Program minimums vary, and jumbo and Non-QM mortgage down payments depend on credit, occupancy, and loan size. Buyers should also budget for the average closing costs in California, including escrow and title fees.

Why Choose LendFriend?

LendFriend Mortgage treats jumbo lending as a core specialty. We pair each borrower with a jumbo lender that fits the property, the financial profile, and the goal of the loan. We charge no hidden fees and run a process built for speed. Buyers across Napa and Sonoma counties can choose a 30-year fixed, a 7/1 ARM, or a flexible Non-QM loan.

Around the Clock

We answer calls and messages 7 days a week to compare jumbo mortgage rates and lender options. Our team finances primary homes, second homes, and investment properties.

Loan Options

Our jumbo financing includes conventional fixed rates, ARMs, bank statement loans, and asset depletion loans. We recommend a structure based on your income, your assets, and how you will use the property.

Get Pre-Approved Quickly

A jumbo preapproval shows a seller you can close on a higher-priced home and strengthens your offer. You can complete the online jumbo loan application in minutes.

Personalized Mortgage Guidance

You work directly with a jumbo mortgage expert who explains each option, prepares the file for approval, and oversees underwriting.

Close in as little as 14 days

We built our process for larger transactions, and many jumbo loans close in as little as 14 days in markets such as Napa, St. Helena, Healdsburg, and Sonoma.

Contact us today to get a custom rate quote for your Napa or Sonoma home financing in less than 2 minutes.