Skip to content

Jumbo Non-QM Loans in Charleston, South Carolina

Buyers come to Charleston for historic homes on the peninsula, beach houses on the barrier islands and golf properties on Kiawah Island and Daniel Island. LendFriend offers jumbo Non-QM options when a borrower's income, assets or property type need more flexibility than a standard jumbo loan gives.

Why Homebuyers Trust LendFriend With Their Jumbo Loans in Charleston

Many Charleston purchases involve a second home, a historic property or a buyer who is relocating with significant assets and little salary. LendFriend arranges jumbo and jumbo Non-QM loans through more than 40 wholesale lenders, so each file can go to a lender whose guidelines match it.

We regularly help buyers finance homes in Charleston, Mount Pleasant, Daniel Island, Isle of Palms and Sullivan's Island, along with Kiawah Island and Seabrook Island. Coastal property, part-year occupancy and retirement income can each affect which lender is the right one.

Jumbo Loans Built Around the Borrower

A physician or executive with W-2 pay may qualify under standard jumbo rules. Retirees, founders and owners of closely held companies often show wealth on a balance sheet and little income on a tax return.

LendFriend offers jumbo loans that account for those differences, including:

  • Bank statement jumbo loans for eligible self-employed borrowers, with income measured from 12 or 24 months of business or personal deposits and no tax returns
  • Asset depletion jumbo loans for eligible borrowers whose investment and retirement accounts are large enough to serve as qualifying income
  • No-ratio jumbo loans for a primary residence only, where eligible borrowers are approved mainly on credit, assets and equity instead of an income calculation

Financing for Historic, Beachfront and Island Homes

Charleston property rarely fits one template. A house South of Broad may be more than a century old. A home on Isle of Palms or Sullivan's Island may sit in a flood zone and be occupied for only part of the year.

We help borrowers finance historic residences, oceanfront homes and golf properties on Kiawah Island and Daniel Island. Lender selection takes into account occupancy, flood insurance, reserves and the source of the borrower's income or assets.

A Faster, More Responsive Jumbo Process

Out-of-state buyers often make an offer after a single visit and need the financing to hold to the contract dates. We review credit, income and assets before the offer and stay in contact with the lender, the appraiser and the South Carolina closing attorney through funding. A prepared borrower may be able to close a jumbo loan in as little as 14 days.

Trusted by Homebuyers

We’ve helped thousands of homebuyers navigate everything from straightforward purchases to highly complex financing, and more than 1,000 reviews speak to the results. Borrowers regularly praise our communication, speed, creativity and follow-through.

Loan Programs To Suit Every Charleston County Borrower's Needs!

We arrange jumbo loan options through more than 40 wholesale lenders for buyers who need wider guidelines than one bank can offer. Qualified Charleston borrowers may choose among bank statement loans, asset depletion loans, and crypto mortgages.

Asset Depletion Loans in Charleston

Asset Depletion Loans in Charleston

Under an asset depletion mortgage, investment balances are converted to qualifying income for a Lowcountry home purchase. Brokerage accounts, retirement funds, and savings may each be included. Retirees and high-net-worth buyers on Kiawah Island and Sullivan's Island may use this structure when a W-2 is absent.

Learn More →

Self Employed Mortgages in Charleston

Self Employed Mortgages in Charleston

Business owners frequently report less taxable income than their companies produce. We arrange self employed mortgage options in which deposits establish income and neither tax returns nor W-2s are requested. The loans serve owners of medical practices, hospitality groups, and professional firms across Charleston and Berkeley counties.

Learn More →

Crypto Mortgages in Charleston

Crypto Mortgages in Charleston

A crypto mortgage lets a buyer finance a home on digital asset holdings without a sale of tokens. Bitcoin and Ethereum balances may support the approval for eligible borrowers, who need not document employment income. Long-term holders buying in Mount Pleasant or on Daniel Island can borrow up to $5M through a jumbo crypto mortgage.

Learn More →

RSU Mortgages For Corporate Employees in Charleston

RSU Mortgages For Corporate Employees in Charleston

A lender may count vested Restricted Stock Units as income even though the borrower sells no shares. Our RSU mortgage program serves equity-compensated professionals at employers such as Boeing, Blackbaud, and Ingevity. Counting stock grants alongside salary may raise the loan amount a borrower qualifies for.

Learn More →

Buy Before You Sell in Charleston

Buy Before You Sell in Charleston

Eligible Charleston owners can purchase a new home ahead of listing the current one through our Buy Before You Sell program. We fund the purchase with a bridge loan secured by the home being sold. Existing equity may fund the down payment, so the offer carries no sale contingency. The sale of the prior home can then close on its own date.

Learn More →

Jumbo No-Ratio Loans in Charleston

Jumbo No-Ratio Loans in Charleston

Purchase or refinance a primary residence above the conforming limit without a debt-to-income ratio. Approval for a no-ratio loan rests on credit, equity, reserves, and mortgage history. The structure may suit borrowers in Charleston whose tax returns understate their means.
Learn More →

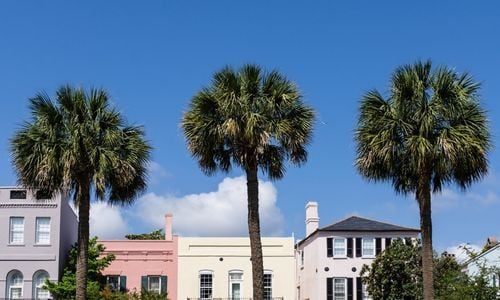
Luxury home near Charleston, South Carolina

Straightforward Qualification That Works for Buyers in Charleston, Mount Pleasant and Kiawah Island

The first question from most buyers in Charleston, Mount Pleasant, Daniel Island and the beach communities is whether they will qualify for a jumbo loan. We answer it at the start by reviewing credit, income, assets, reserves and the property itself.

Clear qualification guidelines for jumbo loans

We lay out the credit, debt-to-income, reserve and document requirements for each loan before you commit to a property. Second homes and investment properties carry different standards, and we explain those as well.

More options for self-employed and retired buyers

Self-employed borrowers may be eligible for jumbo bank statement loans, which rely on deposits in place of tax returns. LendFriend also offers jumbo asset depletion loans for retirees and other buyers whose eligible investment and retirement accounts can support the payment.

Get Started On Your Charleston Jumbo Loan

Your purchase may be a historic home downtown, a beach house on Isle of Palms or a golf property on Kiawah Island. In each case, LendFriend can help you find a home loan in South Carolina suited to your income and assets.

Apply online or schedule a call, and we will review your loan options, current jumbo mortgage rates in Charleston and the paperwork a lender will need. If you are already under contract, we can also discuss what a faster closing may require.

Home in the Charleston area of South Carolina

Jumbo Non-QM Loan Examples for Charleston Buyers

Retirees, founders and second-home owners are common among Charleston's higher-priced buyers, and their income is often hard to document. Each scenario below is illustrative and shows one way a lender can structure jumbo loans for South Carolina homes. The examples use asset depletion loans, bank statement loans and jumbo no-ratio loans. Lenders write a jumbo no-ratio loan on a primary residence only.

$3M Asset Depletion Loan on Kiawah Island

A retired couple from the Northeast is buying a $4.6M home on Kiawah Island and holds $12M in brokerage and IRA accounts. A jumbo asset depletion loan can count those balances as qualifying income for a $3M mortgage. They put $1.6M down, about 35% of the price, and leave the portfolio in place.

$3.3M Cash-Out Asset Depletion Loan in Charleston

A retired surgeon owns a South of Broad home in Charleston worth about $5.5M with a $1.2M mortgage. A jumbo asset depletion loan can qualify a $3.3M cash-out refinance on a $13M portfolio in place of a salary. The loan equals 60% of value, and roughly $2.1M goes to the owner after the old mortgage is paid.

$2.6M Cash-Out Bank Statement Loan in Mount Pleasant

The owner of a Mount Pleasant marine services company holds an Old Village home worth about $4M and owes $1.3M. A jumbo bank statement loan can qualify a $2.6M cash-out refinance on 12 months of business deposits. At 65% of value, the refinance releases about $1.3M for a business expansion.

$2M No-Ratio Loan on Daniel Island

A former technology executive relocating from New York is purchasing a $3.5M home on Daniel Island as her primary residence. A jumbo no-ratio loan, written for a primary residence only, can provide a $2M mortgage with no debt-to-income ratio calculated. She puts $1.5M down, and the loan stands at 57% of the price.

Jumbo Mortgage Options Beyond Charleston

Charleston buyers frequently hold property in a second market. Some are moving for work, some are adding a vacation home, and others spend part of the year elsewhere. Jumbo financing is available from us in many of the states on their lists.

Across South Carolina, we finance higher-priced homes from the Charleston peninsula and Kiawah Island to Hilton Head Island, Greenville, and Lake Keowee. Our jumbo loans in South Carolina serve luxury primary residences, second homes, and investment properties throughout the state.

Summer often takes Lowcountry owners to the mountains. We arrange jumbo loans in North Carolina for buyers in Highlands, Cashiers, and Asheville. Work and family ties also lead clients to Charlotte and Lake Norman, a few hours inland. Others look south to Georgia, where Savannah, Sea Island, and St. Simons Island sit farther down the coast, or to Atlanta for business.

Farther south, Florida draws Charleston buyers to Palm Beach Gardens and Jupiter on the Atlantic side and to Naples on the Gulf. Many owners arrive from the Northeast and keep a home in Connecticut towns such as Greenwich and Darien. We also finance purchases in Tennessee, including Nashville and Franklin.

Whether the next home is on the peninsula, in the mountains, or in another state, we can compare jumbo mortgage options with you before an offer is written.

BORROWER TESTIMONIALS

See Why Jumbo Borrowers Choose LendFriend Mortgage

See how homebuyers across the country have worked with LendFriend Mortgage to navigate larger loan amounts, complex income, and jumbo mortgage financing.

FAQs – Getting a Jumbo Loan In Charleston

What loan amount qualifies as a jumbo loan in Charleston County?

In Charleston County, the 2026 conforming loan limit for a one-unit property is $832,750. Financing above this figure falls into the jumbo loan category.

The 2026 limits for Charleston County appear below, and Berkeley County shares them.

  • Single-unit property: $832,750

  • Two-unit property: $1,066,250

  • Three-unit property: $1,288,800

  • Four-unit property: $1,601,750

Homes in downtown Charleston, Mount Pleasant, Sullivan's Island, and Isle of Palms regularly exceed these thresholds, so jumbo mortgages are the usual form of financing in these markets.

How much can I borrow with a jumbo loan in Charleston?

Borrowers with strong qualifications can obtain a jumbo loan in South Carolina of several million dollars. The ceiling for a given file is a function of credit score, loan-to-value ratio, and reserves. Higher scores and deeper reserves usually bring lower jumbo rates and better terms.

Do jumbo loans require perfect credit?

No. A credit score of 750 or above earns the strongest jumbo pricing. A borrower with a somewhat lower score may still qualify when the file offers compensating strengths, such as more money down or large liquid reserves.

Can I get a jumbo loan in Charleston if I am self-employed or have complex income?

Yes. Jumbo Non-QM programs exist for this purpose, and the two most used are bank statement loans and asset depletion loans. Business owners, consultants, and retirees buying in Mount Pleasant or on the islands may qualify without W-2s or conventional tax returns. South Carolina bank statement loans calculate income from 12 or 24 months of deposits, and jumbo loan amounts reach $7M.

What property types are eligible for jumbo financing in Charleston?

Jumbo lenders finance single-family homes, warrantable and non-warrantable condos, townhomes, and 2–4 unit properties in the Charleston area. We arrange jumbo financing for a South of Broad single house, an I'On residence, a Wild Dunes villa, or a Kiawah Island home. Coastal properties in a mapped flood zone require flood insurance, and we account for the premium when we qualify the loan.


How do jumbo loan interest rates compare to conventional rates?

Jumbo rates in the Charleston area are frequently in line with conventional rates and occasionally below them. Lenders compete for strong jumbo borrowers in established markets such as Mount Pleasant and Daniel Island.

Is an adjustable-rate mortgage a good option for a jumbo loan in Charleston?

It may be, and the length of time you plan to own the home decides the question. A 5/1 or 7/1 jumbo ARM fixes the rate for five or seven years and often prices below a 30-year fixed. The lower early payment can help on a Mount Pleasant or Isle of Palms purchase, which is one reason ARMs have returned for jumbo borrowers. Executives who relocate often and buyers who plan to refinance are the common candidates. Holding period drives the decision, so a borrower should weigh whether an ARM fits a planned sale.

How much equity can I access with a jumbo cash-out refinance in Charleston?

Credit, reserves, and the appraisal all enter the decision, and maximum loan-to-value is commonly about 80% on a primary home and lower on very large loans. Owners in Mount Pleasant, on James Island, and on the peninsula can draw on equity through a jumbo cash-out refinance. The existing mortgage is retired by a larger jumbo loan, and the owner takes the difference in cash. Charleston homeowners with VA entitlement may be able to borrow a higher share of value through a VA cash-out refinance or a VA jumbo cash-out refinance. Monthly mortgage insurance is absent from both VA loans.

Can veterans finance a higher-priced home in Charleston with a VA loan?

Eligible veterans and active-duty service members, including personnel stationed at Joint Base Charleston, may be able to use a VA loan above the conventional limit. For those who qualify, a higher-priced home may be purchased with $0 down and no monthly PMI. A borrower with full entitlement may use VA jumbo loans without a set loan limit.

Can I refinance a jumbo loan in Charleston?

Yes. A jumbo refinance can lower the rate, exchange an ARM for a fixed loan, or take equity out of a high-value Charleston home. Retired owners may also qualify for the new loan with an asset depletion loan in South Carolina, which counts investment balances as income.

What can I do if a bank denied my jumbo loan in Charleston?

A denial at one bank tends to say more about its overlays than about the borrower's capacity to repay. Treatment of bonus income, RSUs, business income, and large asset balances is far from uniform among wholesale jumbo lenders. A broker can move the same file to a lender whose guidelines match it. Buyers under contract still have options after a jumbo loan denial in South Carolina.

How much do I need to put down on a jumbo loan in Charleston?

Jumbo lenders generally require 10% to 20% down on a primary residence in Charleston County. Borrowers with the strongest credit and reserves receive the lowest down payments, while second homes and investment properties call for more. Lenders weigh the reserves left after closing as heavily as the down payment. Minimums are set program by program, and jumbo and Non-QM mortgage down payments rise or fall with credit, occupancy, and loan size.

Why Choose LendFriend?

Jumbo lending is a core specialty at LendFriend Mortgage, not a side offering. We pair each borrower with a jumbo lender that fits the property, the finances, and the goal of the loan. Fees are disclosed in full, and the process is built for speed. We arrange 30-year fixed loans, 7/1 ARMs, and flexible Non-QM options for buyers throughout the Charleston area.

Around the Clock

Calls and messages are answered 7 days a week, and we compare jumbo mortgage rates and lender options on request. Primary homes, second homes, and investment properties in the Lowcountry are all within our scope.

Loan Options

The jumbo financing we arrange runs from conventional fixed rates and ARMs to bank statement loans and asset depletion loans. We recommend a program after reviewing the borrower's income, assets, and plans for the home.

Get Pre-Approved Quickly

Charleston sellers look for a jumbo preapproval as evidence that a buyer can close at a higher price. The online jumbo loan application requires only a few minutes.

Personalized Mortgage Guidance

A jumbo mortgage expert is assigned to you directly, explains each option, prepares the file for approval, and oversees underwriting.

Close in as little as 14 days

Our process was built with seven-figure Lowcountry transactions in mind. Many jumbo loans close in as little as 14 days in competitive markets such as Charleston, Mount Pleasant, Daniel Island, and Isle of Palms.

Contact us today to get a custom rate quote for your Charleston home financing in less than 2 minutes.