“Financing a home with acreage and unconventional retirement income can be overwhelming, but LendFriend Mortgage made the process smooth from beginning to end.
They were always quick to respond, answered every question we had, and explained each step in a way that was easy to understand. We always had direct access to the people actually working on our loan, which made the experience much less stressful.
What really stood out was that even after the loan funded, they continued helping and making sure we understood the next steps. There was never a feeling of ‘the loan closed, good luck.’
We truly appreciated the patience, communication, and support throughout the entire process and would absolutely recommend LendFriend Mortgage, especially for anyone with a unique financial situation or rural property purchase.”
Asset Depletion Loans in South Carolina
Asset depletion mortgages let South Carolina homebuyers qualify on an investment portfolio instead of traditional income. LendFriend structures them for high-net-worth buyers across Charleston, Kiawah Island, Sullivan’s Island, Hilton Head Island, Greenville, and Myrtle Beach, with loan amounts up to $10M.
Why South Carolina Borrowers Choose LendFriend For Asset Depletion Loans
South Carolina homebuyers arrive with wealth held in investment portfolios, retirement accounts, business sale proceeds, and deferred compensation, and their income rarely follows the W-2 pattern conventional underwriting expects. An asset depletion mortgage was designed for exactly that profile.
We work with Charleston executives, Greenville business owners, Kiawah Island second-home buyers, and retirees settling on Hilton Head Island and Lake Keowee. Each is matched to an asset depletion mortgage, a no income verification mortgage, or a jumbo Non-QM mortgage that fits the way their assets are held.

Asset Depletion Loan Experts
Since 2018, our team has originated over $1.5 billion in mortgages, working with the country’s leading asset-based lenders to structure flexible financing for South Carolina homebuyers and second-home buyers.

No Tax Returns Required
A South Carolina asset depletion mortgage functions as both a no tax return mortgage and a no doc mortgage. The asset base does the qualifying, with brokerage accounts, stock portfolios, retirement funds, pensions, annuities, savings, and precious metals all counting toward eligibility.

Up to $10M Loans in South Carolina
Asset depletion mortgages in South Carolina reach up to $10 million, with jumbo loan options for Kiawah Island estates, Sullivan’s Island beachfront, Daniel Island waterfront homes, and Lake Keowee properties.

Fast Approvals Across South Carolina
Pre-approvals issue in as little as 24 hours, and a South Carolina purchase can close in as little as 14 days. As your mortgage broker in Charleston and along the coast, we move quickly when Mount Pleasant, Isle of Palms, Bluffton, or Greenville properties come on the market.
South Carolina Buyers Who Benefit From Asset Depletion Mortgages
South Carolina draws wealth from a few distinct sources. Charleston’s hospital systems, port and manufacturing employers, and a steady stream of relocating executives and retirees produce buyers with substantial assets but income that conventional lenders cannot underwrite cleanly. An asset depletion mortgage was built for that mismatch.
- Charleston executives and physicians at Boeing, Volvo Cars, and the Medical University of South Carolina, with wealth in restricted stock, deferred comp, and partnership equity
- Relocating retirees on Hilton Head Island, Kiawah Island, and Daniel Island drawing on investment portfolios, pensions, and IRA withdrawals rather than active employment income
- Business owners who sold a company and hold the proceeds in brokerage accounts and treasuries while they decide what comes next
- Second-home buyers from the Northeast purchasing on Sullivan’s Island, Isle of Palms, and Seabrook Island with assets that outrun the income on their tax return
- Upstate executives and business owners in Greenville, Landrum, and Fort Mill with wealth in company stock, sale proceeds, and partnership distributions tied to Michelin, BMW, and the Charlotte banks
- Lake and Grand Strand second-home buyers purchasing on Lake Keowee in Seneca and Six Mile, on Lake Murray in Chapin and Lexington, and in Myrtle Beach and Surfside Beach with brokerage and retirement accounts
- Family-trust beneficiaries with multi-generational portfolios and inherited holdings that pay distributions, not W-2 wages
For buyers whose balance sheet says more than their tax return, an asset depletion mortgage opens the door to a South Carolina home loan on portfolio strength alone. No pay stubs, no tax returns, and no employment verification.
From Charleston and Mount Pleasant to Bluffton and Hilton Head Island, LendFriend Mortgage structures South Carolina asset depletion mortgages and jumbo Non-QM loans around investment portfolios, sale proceeds, and trust-held wealth.
How an Asset Depletion Mortgage Benefits South Carolina Homebuyers
An asset depletion mortgage in South Carolina means buying a home without liquidating investments. The portfolio stays intact, and the loan closes on the strength of the wealth you have already built.
- Qualification on your portfolio, not a pay stub. No W-2s, tax returns, or employment paperwork in underwriting. The asset base is what gets reviewed.
- Loans up to $10M+ on South Carolina properties. Most asset depletion mortgages reach $10M, and jumbo asset depletion mortgages can go higher when the portfolio supports it.
- Coverage across South Carolina’s coastal, Upstate, and lake markets. Primary residences, second homes, and investment properties all qualify.
- Closings on a shorter timeline. Asset-focused underwriting removes the income paperwork that slows a conventional mortgage.
- Investments stay invested. You will not have to sell positions or trigger avoidable tax events to fund a down payment.
Get an Asset Depletion Loan Rate Quote
Where an Asset Depletion Mortgage Fits a South Carolina Buyer
Many South Carolina buyers hold significant investment portfolios alongside income that a standard mortgage application cannot capture. Conventional underwriting struggles with that mismatch, and a South Carolina asset depletion mortgage resolves it by qualifying you on the portfolio itself.
South Carolina’s high-net-worth buyers split between Charleston’s executive and physician market, from Mount Pleasant to Daniel Island, and the second-home and retirement markets on Kiawah Island, Isle of Palms, and Hilton Head Island. Greenville, Fort Mill, and the communities around Lake Keowee and Lake Murray add a third group of executives, business owners, and retirees. Asset depletion mortgages qualify each group on the strength of what they have already saved.
South Carolina asset depletion mortgages are a strong fit for:
- Executives and physicians paid through stock vesting, deferred compensation, or partnership distributions
- Founders and business owners who sold a company and now hold the proceeds in brokerage accounts
- Retirees and relocating buyers bringing substantial liquid wealth to the South Carolina coast
The divisor a lender uses decides how large a jumbo asset depletion loan on the South Carolina coast can be. We run that calculation before a Kiawah Island offer or a Sullivan’s Island cash-out refinance goes forward.
With a South Carolina asset depletion mortgage, your net worth qualifies you for the loan, and the portfolio stays invested.
Asset Depletion Loan Options Beyond South Carolina
Many South Carolina buyers own property across a state line, and the qualification method travels with them. A Charlotte family buying in Fort Mill or on Lake Keowee may finance the primary home with a North Carolina asset depletion loan on the same portfolio.
Georgia is the other common pairing. Atlanta families in Buckhead and Alpharetta who keep a second home on Hilton Head Island or Lake Keowee may qualify for a Georgia asset depletion loan using the same statements. Savannah and Sea Island owners buying in Bluffton or Charleston may do the same. For larger Atlanta homes, the lender’s divisor sets the size of a jumbo asset depletion loan in Fulton County.
Second homes and relocations follow the same pattern. Nashville executives who keep a beach house on Isle of Palms may use a Tennessee asset depletion loan for the primary residence. Charleston retirees who winter in Naples or Palm Beach may close on a Florida asset depletion loan without selling a position. An executive moving between Greenville and Dallas or Austin may qualify for a Texas asset depletion loan on the same accounts.
Whether the purchase stays in Charleston or reaches a second home in another state where LendFriend is licensed, we settle the financing before an offer goes in.
The 3-Step South Carolina Asset Depletion Mortgage Process
Our team has guided South Carolina homebuyers through each step of the asset depletion process, with deep familiarity in Fannie Mae, Freddie Mac, and Non-QM lending guidelines.
Step 1: Identify Your Eligible Assets
We begin by reviewing the assets that can be used for qualification. This typically includes checking and savings accounts, CDs, brokerage accounts, precious metals, stocks, bonds, mutual funds, IRAs, and 401(k)s. In certain cases, real estate holdings may also be included, depending on the program.
Step 2: Apply Asset Valuation
Lenders do not use the full value of every asset. Instead, they apply a conservative percentage to account for liquidity and market volatility, converting your total holdings into a stable and verifiable income base for underwriting purposes.
Step 3: Convert Assets Into Monthly Income
Your eligible assets are divided over a standard term, typically 60 to 120 months, to produce a monthly qualifying income. That income drives your debt-to-income ratio and loan eligibility, allowing you to qualify without W-2s, pay stubs, or tax returns.
How We Structure Asset Depletion Loans for South Carolina Borrowers
From Charleston and Kiawah Island purchases to Isle of Palms and Sullivan’s Island homeowners pulling equity out to diversify and fund retirement, we help South Carolina borrowers use their investments, retirement accounts, and other eligible assets to qualify when tax returns do not tell the full story. The examples below are illustrative and show how we structure these loans.
Charleston Buyer Finances a $2.8M Peninsula Home
A founder who sold a software company wanted a $2.8M home on the Charleston peninsula without paying cash and liquidating the invested proceeds. We used the brokerage accounts left after closing as qualifying income. He put $700,000 down and financed $2.1M with the portfolio intact.
Kiawah Island Buyer Keeps Liquidity on a $4.5M Second Home
A buyer purchasing a $4.5M second home on Kiawah Island could have paid cash but did not want to sell investments to do it. We tested the down payment against the assets left to qualify and used the portfolio as income. She closed with $900,000 down and a $3.6M mortgage.
Isle of Palms Homeowner Pulls $1.6M Out to Diversify
An Isle of Palms homeowner with a $4M home and a $1M mortgage wanted cash out to diversify beyond the property. We used his eligible investments as qualifying income for the larger payment. The refinance closed at $2.6M with roughly $1.6M in proceeds.
Sullivan’s Island Retiree Completes $2M Cash-Out Refinance
A retired couple on Sullivan’s Island wanted to replace a $500,000 mortgage on their $4.8M home with a $2M loan to fund retirement. Pension income alone fell short, so we used their IRAs and brokerage portfolio as qualifying income. They closed with roughly $1.5M in proceeds.
Stronger Negotiating Position when Buying a Home
The equity in your current home is unlocked and used as a downpayment on your new home; meaning no sales contingency required! Sellers HATE sales contingencies. Without a sales contingency, your offer is stronger, increasing your chances of buying your next home with ease.
Get the Highest and Best Sale Price
Without feeling pressured to sell quickly, you can wait for the best offer on your current home. List your home at the best time, market it effectively, and attract more competitive offers. With no rush, you can negotiate better terms and get the highest selling price.
Reduced Stress
Don't worry about finding temporary housing or organizing multiple moves. Avoid the chaos of having to coordinate the sale of your current home and the purchase of a new one. Transition seamlessly from one home to another and reduce stress or anxiety, making the moving process more manageable and organized.
Time for Improvements
Make necessary renovations or updates to your new property before you move in. Painting, remodeling, or other improvements would be more challenging if you were already living there. Moving into a freshly updated home (instead of living in it during renovations) is just so much nicer!
Get Pre-Approved for a South Carolina Asset Depletion Mortgage
Connect with LendFriend and start your mortgage approval.
See Why Asset Depletion Borrowers Choose LendFriend Mortgage
See how retirees, investors, and borrowers with substantial assets have worked with LendFriend Mortgage to qualify for a home without relying solely on traditional employment income.
“The team did a great job from start to finish. It was a pleasure working with them.”
“I had a phenomenal experience working with Eric, Morgan, and Crystal at LendFriend and cannot recommend them enough. They helped me secure a 30 year fixed rate mortgage enabling me to purchase an amazing home for my family.
I reached out through their website contact form on a Saturday night, and Eric connected with me the very next morning (Sunday) to discuss asset depletion mortgages and my goals.
Eric called regularly with updates on potential lenders, rates, and more. It was an amazing experience from start to finish and I truly felt they would move heaven and earth to get me the financing I needed.
Thank you, Eric, Morgan, Crystal, and the entire LendFriend team!”
“My husband just retired and we are officially snowbirds thanks to Lend Friend. We just bought a winter home in Boca. Everyone was so lovely to work with. Eric, Crystal and Morgan answered all our questions and made sure we were comfortable from start to finish.
Im so excited for all my grandchildren to visit me during the holidays.”
“I’m in early retirement and currently have no traditional income, and I needed a loan to purchase a new home. I assumed getting financing under those circumstances was going to be extremely difficult, if not impossible.
LendFriend made what seemed impossible surprisingly simple. They understood my situation, found a way to make the loan work, and most importantly, got everything closed on time.”
“For the past two years I have been contemplating buying a home. I was referred to Lendfriend mortgage and when I say the experience from start to finish was an awesome experience. The WHOLE TEAM was there for me.
The Professionalism and support was truly unbeatable. 100% recommending Lendfriends mortgage.”
5/5 Star Reviews on Google, Zillow, and Experience.
See How Much Mortgage Your Assets Could Support
Use our Asset Depletion Mortgage Calculator to estimate how your savings, investment accounts, retirement funds, and other eligible assets could be used to qualify for a mortgage without relying entirely on traditional income.
Calculate Your Buying Power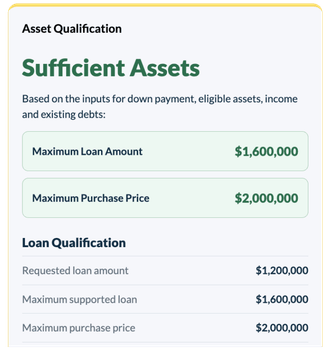
FAQs: Asset Depletion Loans in South Carolina
Which assets qualify for a South Carolina asset depletion mortgage?
Qualifying assets for a South Carolina asset depletion mortgage include brokerage accounts, savings, CDs, stocks, bonds, cryptocurrency, mutual funds, IRAs, 401(k)s, and precious metals. Real estate equity and business holdings can also count under certain programs, and the full list sits in our guide to asset depletion mortgage requirements.
Can I qualify in South Carolina without W-2 income?
Yes. A South Carolina asset depletion mortgage qualifies you on verified investment and retirement holdings rather than on W-2 income, so a retiree on Hilton Head Island or a founder between companies in Charleston can be approved with no employment income at all.
How does a South Carolina asset depletion mortgage turn assets into income?
Eligible assets are divided over a fixed term, usually 60 to 120 months, to produce a monthly income figure that drives the debt-to-income calculation. The asset depletion mortgage calculator shows how a given portfolio translates into qualifying income before you apply.
What credit score do I need for an asset depletion mortgage in South Carolina?
Credit matters on South Carolina asset depletion programs no matter how strong the asset position is. Most lenders accept a minimum score of 680, and a score above 700 opens up the best pricing. The higher the score, the better the terms you can qualify for.
How large can a South Carolina asset depletion mortgage be?
South Carolina asset depletion mortgages typically reach $10M for high-net-worth borrowers, with the ceiling tied to portfolio size, property type, and lender program. Jumbo Non-QM structures can go higher for the right file, and comparing asset depletion against traditional income on a jumbo loan shows which path produces the larger approval.
Are asset depletion mortgages available in Greenville, Fort Mill, and on Lake Keowee or Lake Murray?
Yes. We arrange asset depletion mortgages across the Upstate and the lakes, including Greenville, Landrum, Fort Mill, Seneca, Six Mile, Chapin, and Lexington. The same qualification applies to higher-priced homes across South Carolina, and lake properties with docks or few comparable sales receive an early appraisal review.
Can I use an asset depletion mortgage for a second home on Kiawah Island or Hilton Head Island?
Yes. Kiawah Island, Sullivan’s Island, Isle of Palms, and Hilton Head Island are all eligible markets, and the program covers primary residences, second homes, and investment properties. South Carolina assesses second homes at 6% of value rather than the 4% owner-occupied rate, so we build the higher tax bill into the qualifying numbers, as our guide to retirement mortgages explains.
Can cryptocurrency count toward a South Carolina asset depletion mortgage?
Yes. Eligible Bitcoin and Ethereum holdings can be used in certain crypto mortgage programs as part of an asset depletion calculation. The lender assigns an eligible value to the crypto and converts it into monthly qualifying income, so you qualify without selling or pledging the digital assets as collateral, and the crypto can be combined with stocks, retirement accounts, cash, and other qualifying assets. Borrowers with concentrated crypto positions buying in South Carolina can also look at a jumbo crypto mortgage for larger loan amounts.
Do I have to sell investments to qualify for a South Carolina asset depletion mortgage?
No. Your balances are used only to calculate qualifying income, and the accounts remain invested through closing and afterward. There is no requirement to withdraw the calculated amount each month.
Can I use an asset depletion mortgage for a cash-out refinance in South Carolina?
Yes. A homeowner in Charleston, Myrtle Beach, or Surfside Beach may replace the current mortgage with a larger one and qualify on eligible assets. The equity in the home sets how much cash a jumbo cash-out refinance can release, and the existing portfolio has to support the new payment.
Why Work With a HNW Mortgage Broker Who Understands Asset-Based Lending?
At LendFriend Mortgage, we're more than a lender. We're your trusted HNW mortgage broker, dedicated to helping you qualify for the right asset-backed loan without the burden of traditional documentation. As a top-tier asset-based mortgage lender, we specialize in mortgages for high-net-worth individuals who prefer flexible solutions such as asset depletion loans and non-QM mortgages.
Our user-friendly tech and transparent process make it easy to compare loan options, get pre-approved, and close quickly.
Around the Clock
We're available 7 days a week, 365 days a year to help you compare rates, explore asset-based lending options, and move forward confidently, whether you're buying, refinancing, or upgrading.
Asset-Based Mortgage Solutions for High-Net-Worth Borrowers
Our asset depletion mortgage programs let you qualify on the strength of your assets rather than traditional income, so you can secure the home you want without compromise or delay.
Get Pre-Approved Quickly
Apply online to get pre-approved for an asset-based loan in minutes. It’s the fastest way to strengthen your offer and move forward with confidence.
Competitive Rates with No Hidden Fees
We help you secure competitive asset depletion loans with fair, transparent pricing. No junk fees, no unnecessary points, just financing that reflects your financial strength.
Personalized Mortgage Guidance
You’ll work one-on-one with a dedicated mortgage expert who specializes in asset-based loans and will guide you through the best-fit programs based on your net worth and financial strategy.
Close in just 3 Weeks
Our process is built for speed. Most asset-based loans and non-QM mortgage products can close in just 3 weeks, often faster than conventional financing.
Learn More About Asset Depletion Loans
Our Learning Center gives you access to helpful resources on asset depletion mortgages, qualifying with retirement and investment assets, buying a home in South Carolina, and refinancing. Read some of our featured articles below to learn more about asset depletion loans and how they work.

Other Non-QM Mortgage Solutions for South Carolina Borrowers
With access to more than 40 wholesale lenders, LendFriend Mortgage can match South Carolina borrowers to another Non-QM loan when an asset depletion mortgage is not the best fit.
No-Ratio Loans
Qualify on credit, equity, reserves, and mortgage history, with no debt-to-income ratio calculated. No-ratio loans are available for primary residences only.

Bank Statement Loans
A bank statement loan lets entrepreneurs and business owners in Charleston, Greenville, and Myrtle Beach qualify on 12 or 24 months of deposits instead of tax-return income.
DSCR Loans
A DSCR loan qualifies a South Carolina investment property on its rental income, without tax returns, W-2s, or personal income documentation.