
“Super impressed with how fast and smooth the whole process was — especially given my complex RSU comp structure that traditional banks kept discounting.
Eric and the team had no problem including my full base + RSU compensation. They were extremely fast, set clear expectations from the start, and followed through on everything they promised.
Honestly one of the easiest and most stress-free mortgage experiences I’ve ever had. Highly recommend!”
Average Mortgage Rates Today
Use the national averages below as a starting point, then get a personalized LendFriend quote based on your credit, down payment, property, and loan type. Your actual rate may be higher or lower than the benchmark.
Where Mortgage Rates Stand Today
The rates below are based on the Optimal Blue Mortgage Market Indices (OBMMI), which track average mortgage rates locked nationwide on the previous business day. They are benchmarks, not individual quotes; your rate will depend on factors like credit, down payment, loan type, and property.
Source: Optimal Blue Mortgage Market Indices, updated each business day. National averages, not rates offered by LendFriend Mortgage.
Sign Up for Our Weekly Rate Alert and Never Miss a Rate Drop
Join the 2,000+ subscribers receiving our lowest advertised rates.
Mortgage pricing moves with the bond market, often more than once in a single day, and a national average published in the morning can be stale by the afternoon. Each week we send the rates we are quoting across conventional, jumbo, VA, and Non-QM loans, along with a short note on what moved and why, so you know when it is time to lock.
Sign Up for Our Weekly Rate Alert and Never Miss a Rate Drop
Join the 2,000+ subscribers receiving our lowest advertised rates.
Mortgage pricing moves with the bond market, often more than once in a single day, and a national average published in the morning can be stale by the afternoon. Each week we send the rates we are quoting across conventional, jumbo, VA, and Non-QM loans, along with a short note on what moved and why, so you know when it is time to lock.
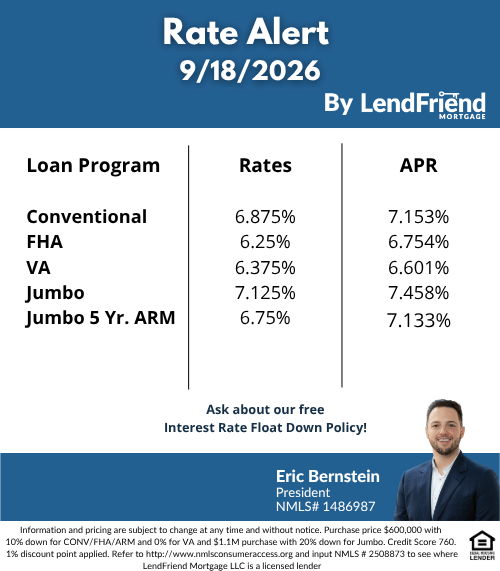
Example of This Week's Mortgage Rate Alert
Mortgage Rate FAQs: What You Need to Know and How LendFriend Helps You Save
How are average mortgage rates calculated?
The national mortgage rate averages shown above come from the Optimal Blue Mortgage Market Indices (OBMMI). These rates represent a daily average of actual locked rates across thousands of lenders nationwide. The index includes a wide range of borrowers, property type (condo vs house), loan type (primary, secondary, investment), credit scores, and loan-to-value ratios, so it reflects general market pricing rather than a specific lender’s rate sheet.
Why are LendFriend's rates often lower than the national average?
LendFriend Mortgage is a family-owned, independent mortgage broker. That means we work with many different lenders to shop around and find you the best deal — not just the rates from one bank. Because of this, we can often offer access to wholesale mortgage rates that are lower than the national average.
We’re a small business, not a big bank. Unlike large lenders with high overhead costs, we keep things lean so there’s less cost passed on to you. On top of that, we help match you with the right loan program for your needs — and you may qualify for special discounts or lender credits through us that you wouldn’t get elsewhere, helping you save even more.
How can I get a mortgage rate lower than the average?
Working with a mortgage broker like LendFriend is one of the best ways to secure a rate below the national average. We shop multiple lenders for you and negotiate pricing based on your specific situation. Additionally, improving your credit score, lowering your debt-to-income ratio, and making a larger down payment can help you qualify for better rates.
Why do mortgage rates change every day?
Mortgage rates are tied to movements in the bond market, particularly mortgage-backed securities. As economic data, Federal Reserve policies, and investor sentiment shift, bond yields move — and mortgage rates follow. That’s why rates can change daily (or even within a single day). Factors like inflation reports, jobs data, and geopolitical events can all influence mortgage pricing.
What’s the difference between conforming, jumbo, VA, FHA, and USDA rates?
Each loan type has its own eligibility criteria, risk profile, and secondary market pricing:
Conforming loans (up to the Fannie Mae and Freddie Mac limits) usually carry the best rates for well-qualified borrowers, and most conventional loans fall into this category.
Jumbo loans exceed the conforming limit and are priced by the lender holding the loan, which can place them above or below conforming depending on the week.
VA loans for veterans and active-duty service members are government-backed, require no down payment, and routinely price below conforming; a VA home loan also carries no monthly mortgage insurance.
USDA loans (for eligible rural areas) carry a similar guarantee and can offer below-market rates with reduced fees.
FHA loans may have competitive note rates, but the mortgage insurance premiums raise the overall cost.
We offer a wide range of mortgage loan options and can help you find the one that suits you best.
Are jumbo mortgage rates higher than conforming rates?
Not necessarily. Jumbo pricing is set by the banks and investors that hold those loans on their own balance sheets rather than by Fannie Mae or Freddie Mac, so it moves with their appetite for high-balance borrowers. In many weeks a well-qualified buyer with strong reserves can secure a jumbo loan at or below the conforming average shown above. Veterans purchasing above the conforming limit have a further option: a VA jumbo loan keeps the zero-down benefit and often prices below both.
Why don’t Non-QM rates appear in the national averages?
The OBMMI indices track conforming, jumbo, FHA, VA, and USDA locks, so they do not capture loans underwritten outside agency guidelines. Non-QM loans are priced by individual investors and vary with the documentation used to qualify. A bank statement loan for a self-employed borrower, an asset depletion mortgage that qualifies on liquid assets instead of income, and a DSCR loan underwritten on rental cash flow each carry their own rate sheet, generally a modest premium over the agency averages in exchange for that flexibility.
Do mortgage rates vary by state?
The note rate itself is priced on national capital markets, so two borrowers with the same credit profile in Austin and Miami will generally see similar quotes. What changes from state to state is the cost around the rate: property taxes, title and escrow fees, homeowners insurance, and appraisal pricing all affect your APR and cash to close. Conforming loan limits differ by county as well, so a loan amount that is jumbo in Texas can still be conforming in the high-cost counties of California. LendFriend lends in Florida, Colorado, and more than a dozen other states, and prices every file against the same lender panel wherever the property sits.
Should I lock now or wait for rates to fall?
No one times the bottom reliably, and a rate that looks high today can look ordinary in hindsight. The better question is whether the payment works for you now. If it does, locking removes the risk of a move against you, and if rates fall meaningfully after closing, a refinance lets you capture the lower rate. Our mortgage calculators show what a quarter-point change means in monthly terms, so you are deciding on numbers rather than headlines.
BORROWER TESTIMONIALS
See Why Borrowers Call Us the Best Mortgage Broker
From first-time homebuyers and business owners to jumbo borrowers and clients with complex income, see what borrowers across the country say about working with LendFriend Mortgage.
★★★★★
“LendFriend is the absolute best. I found them after I was denied by a lender due to an appraisal issue. I spoke with dozens of lenders, but LendFriend was the only one that could figure out a solution. They were able to close my jumbo loan in less than 3 weeks and hit my closing date. If you need a lender to step in and save the day, call LendFriend!”
“I recently used LendFriend for my home purchase, and they were fantastic! The team was professional, responsive, and truly caring. They explained everything clearly, answered all my questions, and made the process smooth and stress-free.
What really sets them apart is their forward-thinking approach—they accept cryptocurrency holdings as proof of income/assets, which was a game-changer for me and made qualifying so much easier. Communication was excellent, they secured a great rate, closed on time with no hidden fees, and their online portal was super easy to use.
If you want a modern lender that puts you first, embraces crypto, and delivers results, choose LendFriend. I’ll recommend them to everyone—thank you for making my dream home possible!”
“As a 1099 worker with non-traditional income history, Eric was able to think outside the box and help me find a mortgage for my first home. The company was always problem-solving and the process was seamless. I have already recommended them to several other friends and colleagues. If you are a non-traditional borrower or are looking for someone that can come up with creative solutions, check out LendFriend!”
“The team at LendFriend made buying our home in Florida so easy. We had an expiring lease and LendFriend was able to move very quickly to get us closed in under 30 days before the lease ended. They also got us a great rate on a jumbo loan and were available day and night to answer all of our questions. If you’re looking for a mortgage broker that makes the process stress-free while still getting you a great rate, you have to call LendFriend.”
“LendFriend made my homebuying experience so easy. As a business owner, I heard horror stories about how hard it can be for guys like me to get a mortgage. Thankfully I found LendFriend. Eric and the team had me approved in no time. My rate was great and they closed on time. Couldn’t ask for more.”
“Financing a home with acreage and unconventional retirement income can be overwhelming, but LendFriend Mortgage made the process smooth from beginning to end.
They were always quick to respond, answered every question we had, and explained each step in a way that was easy to understand. We always had direct access to the people actually working on our loan, which made the experience much less stressful.
What really stood out was that even after the loan funded, they continued helping and making sure we understood the next steps. There was never a feeling of “the loan closed, good luck.”
We truly appreciated the patience, communication, and support through the entire process and would absolutely recommend LendFriend Mortgage, especially for anyone with a unique financial situation or rural property purchase.”
“Eric and his team went above and beyond to help us with our home purchase. Our realtor recommended LendFriend to us and we couldn't have been happier with the recommendation. They were so nice and answered every question we had no matter how insignificant it seemed.”
5/5 Star Reviews on Google, Zillow, and Experience.